Investment Committee Summary
| Rating | HOLD |
| Internal 5-tier | HOLD |
| Classification · conviction | cyclical compounder · medium |
| Evidence | 8/8 load-bearing inputs sourced |
| Triangulated fair value | $97.05 (-9% vs spot · triangulated FV) |
| 12-mo scenario PWEV | $111 (+4% vs spot · 12m PWEV) |
| Next catalyst | 2026-11-05 — Quarterly earnings |
| Primary thesis-break | Total revenue growth (YoY) < 0.06 (2 consecutive prints) |
Decision detail — rating tables & Research OS strip
Rating: HOLD
Internal 5-tier: HOLD · cyclical compounder · analyst conviction: medium
| Metric | Value |
|---|---|
| Current Price | $107 |
| Triangulated Fair Value | $97.05 (-9% vs spot · triangulated FV) |
| 12-mo Scenario PWEV | $111 (+4% vs spot · 12m PWEV) |
| Forward P/E | 16.1x |
| Market Cap | $16B |
| 52-Week Range | $70.82–$165 (intraday high and low over the trailing 52 weeks of the stock's own daily bars) |
EPS basis for the forward P/E and all scenario multiples: consensus forward EPS (broker-adjusted, non-GAAP).
Methodology: Valuation triangulated across three weighted anchors — an intrinsic DCF, a scenario-weighted PWEV and a Monte Carlo median (Student-t + regime switching). Anchors are blended at fixed declared weights, each counted separately; the Monte Carlo, the scenario PWEV and the DCF's exit-multiple terminal all rest on the same base multiple, so where they agree it is partly by construction — not independent corroboration. Figures reconciled to Alpha Vantage 2026-10-09. Each chart below sits with the part of the thesis it evidences.
General research, published identically to every reader. Not personal financial advice. Figures as of the analysis date; verify before acting.
Decision Support — Research OS jump to detail ↓
| Research conviction | Exp. return (1y) | Rules stance | Next catalyst |
|---|---|---|---|
| 50.7/100 (20th pct) | +7% 1yr expected | Hold | 24d — Quarterly earnings |
Full breakdown — conviction components, probability-return distribution, decision rules, factor & portfolio interaction and the catalyst timeline — in the Decision Support sections below. Model output for research; not personal financial advice.
📎 Download the full model (Excel) — DCF line items, scenarios, sensitivity, assumptions, and extended fundamentals.
Recommendation: HOLD
Balanced: triangulated fair value $97.05 (-9% vs spot); the outcome hinges on P/E Multiple. The debate is P/E Multiple — fundamentally a multiple/regime call.
Investment Thesis
At $107 (12 October 2026) the market pays 16 times forward earnings for Akamai, treating the base path — steady security growth, managed delivery decline, early compute monetisation — as largely delivered. The engine is less generous. The probability-weighted value of $111 and the base-path target of $110 sit below the current price; only a minority of simulated paths finish above spot; and most outcome variance sits in the multiple, not in earnings. Triangulated fair value of $97.05 leaves the shares fairly valued against the anchor set, -9% against spot, and the peer-median forward multiple would imply materially less again. Capital intensity is heavy for a software name, while net debt of ~$4.9B limits balance-sheet flexibility against a segment operating margin of 12% (reported GAAP, TTM to Jun 2026). The rating is HOLD: the base case is priced, the anchor set sits lower, and the payoff skew is flat. The most damaging risk is structural — AI-native architectures eroding delivery while platform bundles commoditise security — whose target sits below the 52-week low.
Narrative drafted 2026-08-16 by claude-opus-5 under supervision; reviewed by Marinus 2026-08-16.
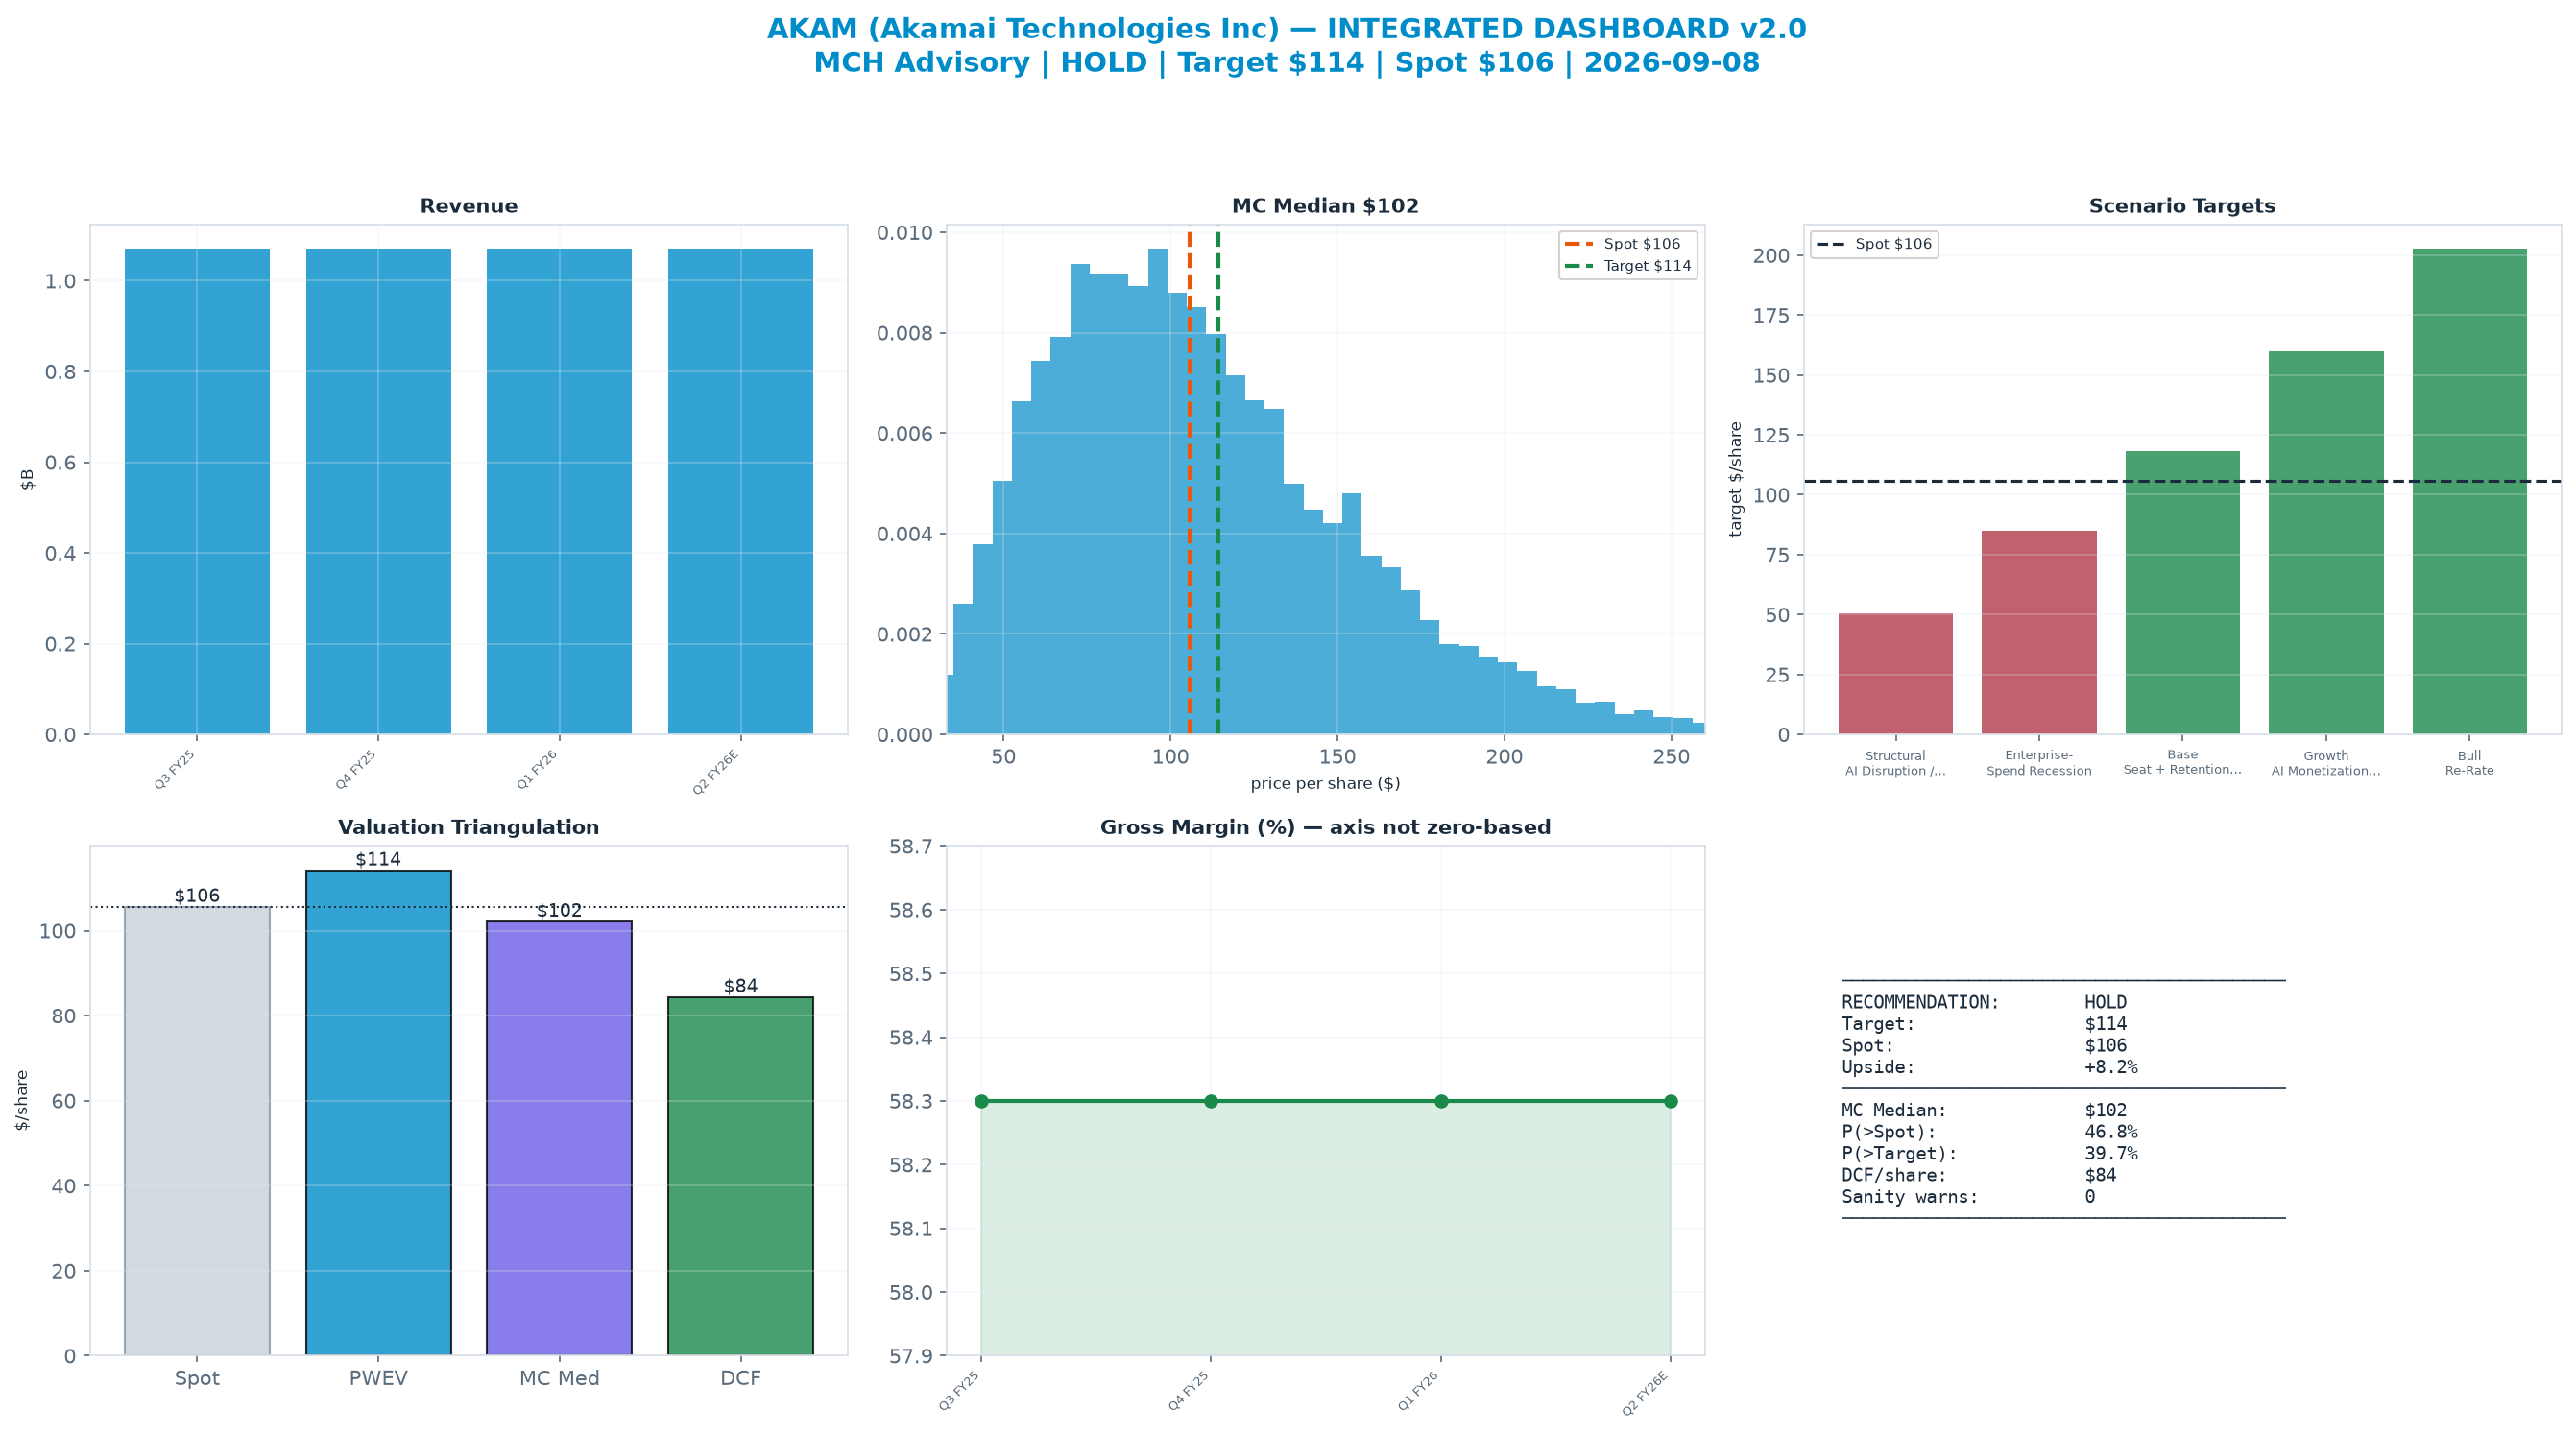
The dashboard below is the whole argument on one page: spot ($107) against each valuation anchor, the scenario tree, technicals and the options-implied move.
Anti-Thesis (The Real Bear Case)
The structural bear is mechanical, not rhetorical. Delivery keeps shrinking as hyperscalers and AI-native application stacks internalise content and edge distribution, and the decline accelerates past the managed price-downs the base case assumes. Security, the growth pillar, commoditises as larger platforms bundle equivalent controls into suites customers already own, compressing net retention. Meanwhile the compute buildout absorbs a heavy share of revenue in capital spending before the derived revenue is large enough to carry it, so margins fall well below 12% (reported GAAP, TTM to Jun 2026) as depreciation catches up with the spend. Earnings compress while the market re-rates the equity from a software multiple to an infrastructure one, from 16 times toward the low teens. That path lands below the 52-week low, and net debt of ~$4.9B removes the repurchase cushion that has supported the share count.
Key Debate
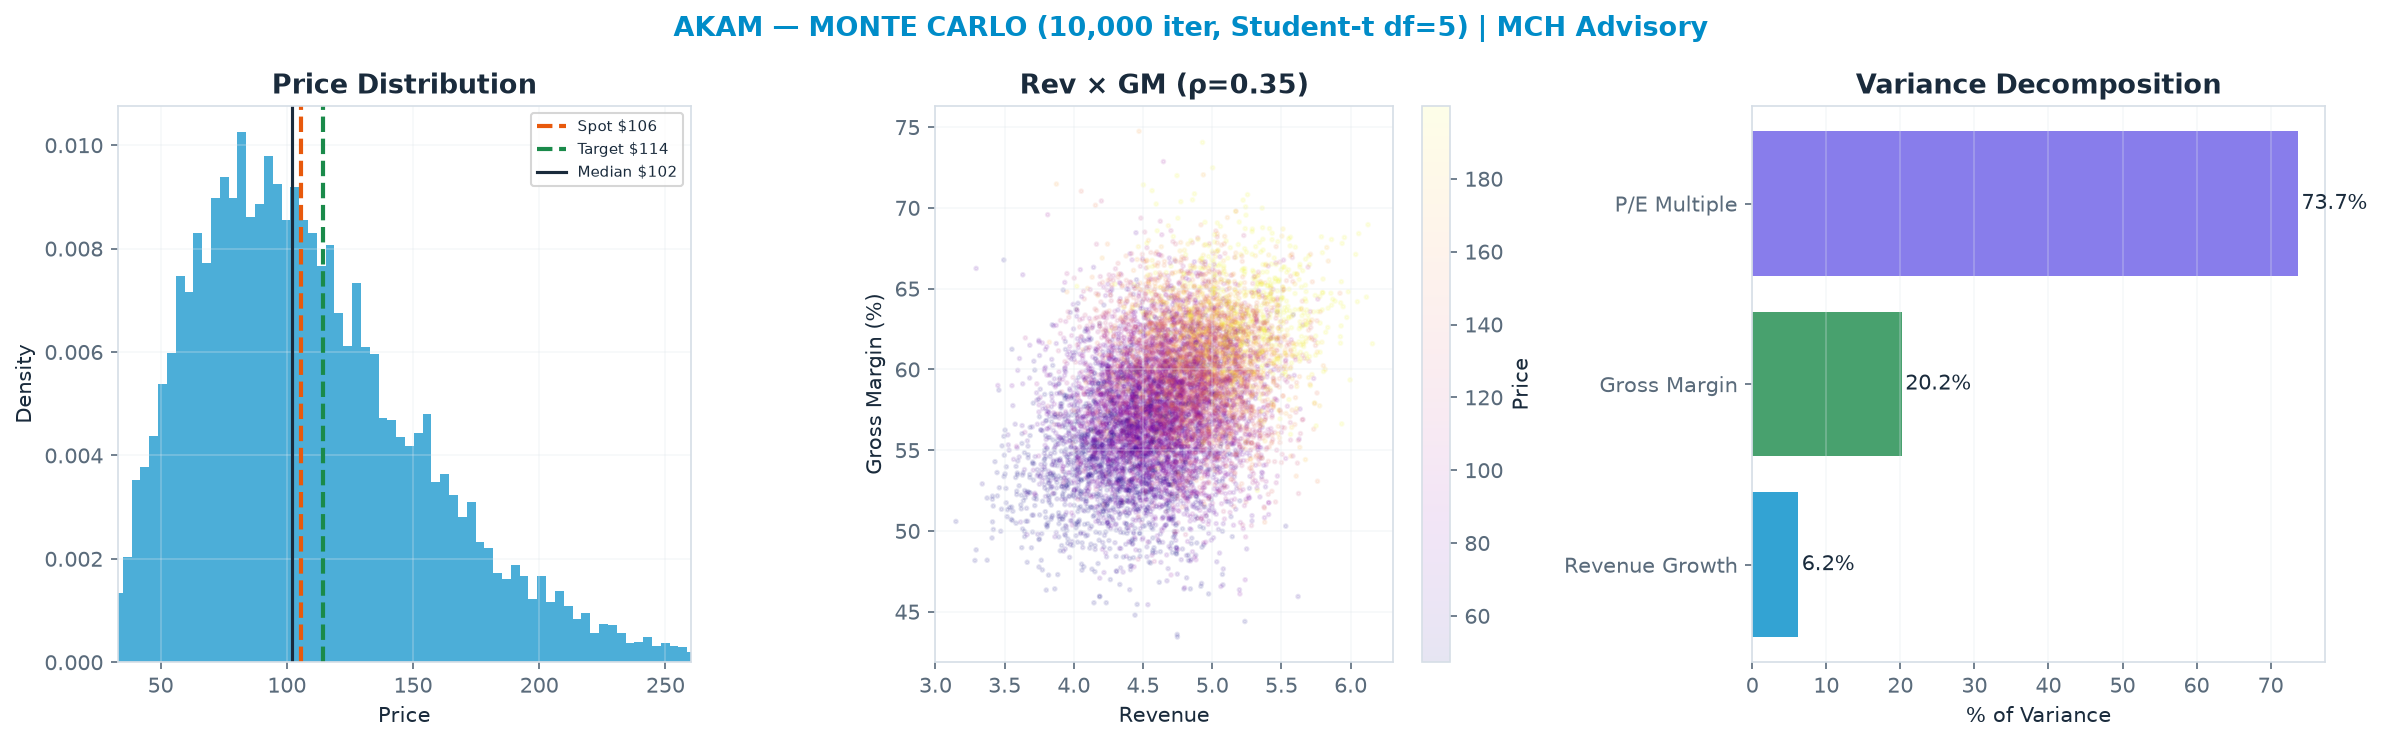
P/E Multiple explains 73% of Monte Carlo outcome variance — i.e. value is set by the multiple the market will pay, a rate/sentiment regime bet as much as an earnings bet.
What the Market Is Pricing In
At the current price, the market pays 16.1× consensus forward EPS, vs the house DCF terminal 14.0×, and a peer median 10.0×. The house DCF sits 20% below spot, so the market is pricing in more than the house case — roughly 1.7pp of revenue CAGR.
Variant perception: the house view is below-consensus, and the thesis is primarily growth-driven.
| Metric | Consensus | House | Importance |
|---|---|---|---|
| Revenue | 4.5 | 4.7 | High |
| EPS | 6.6 | 6.6 | Medium |
| Target price | 158.9 | 109.7 | Medium |
Scenario Analysis
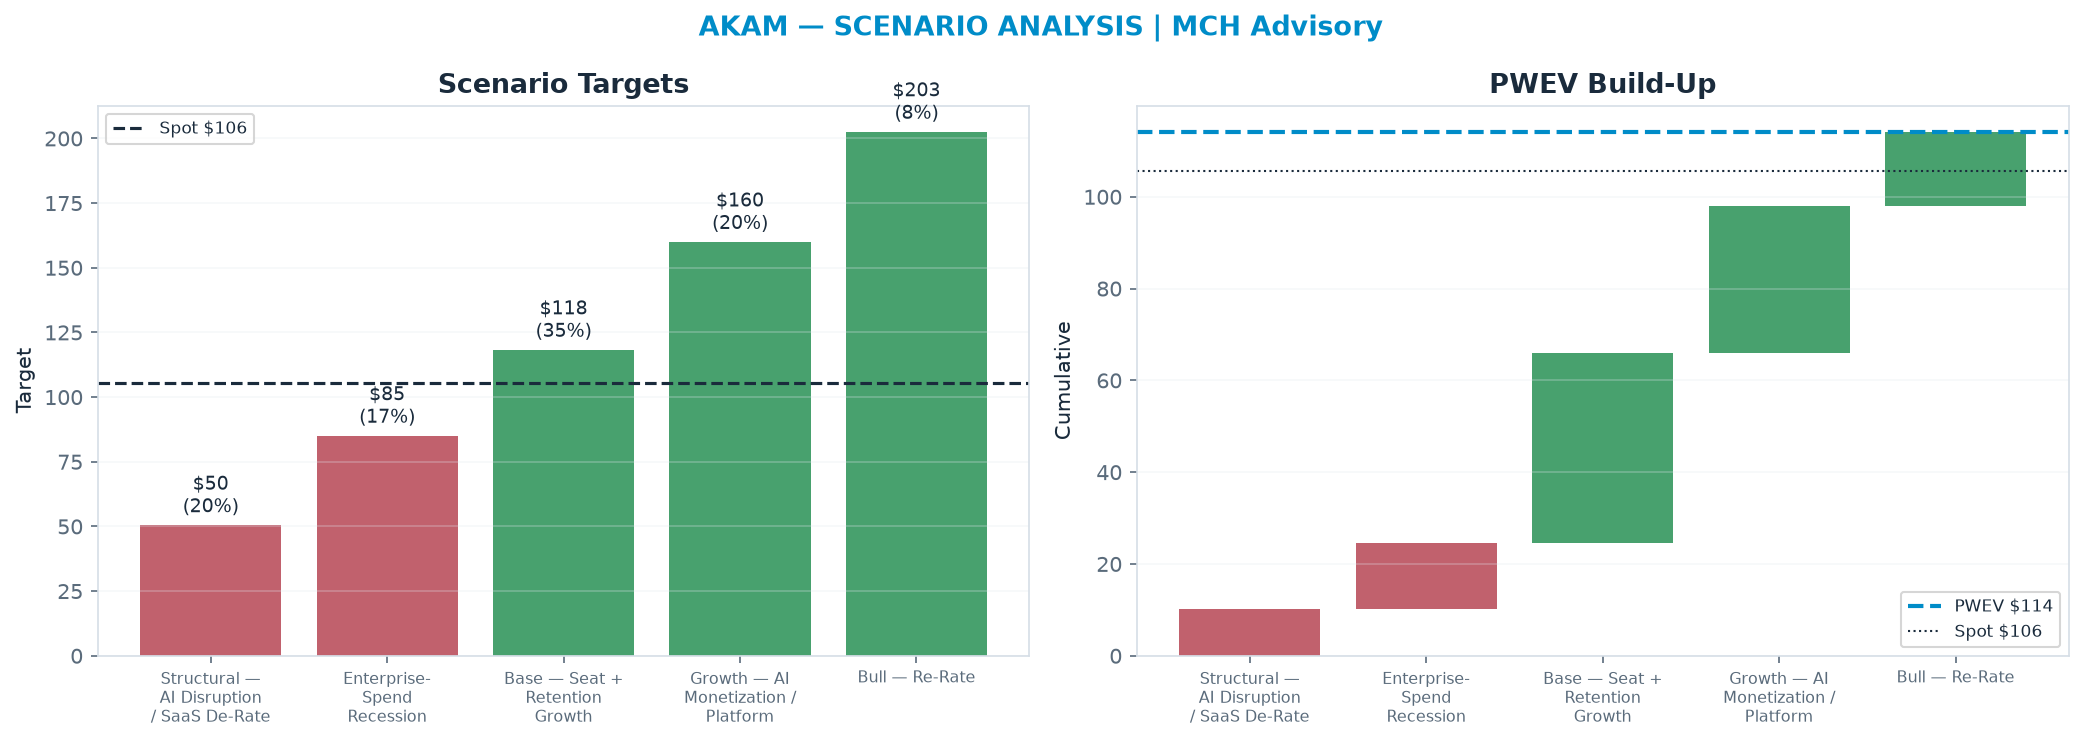
The scenario tree spans a structural 'Structural — AI Disruption / SaaS De-Rate' downside ($50.50) to a 'Bull — Re-Rate' bull case ($203); the probability-weighted blend (PWEV $111) is +4% versus spot.
| Scenario | Probability | Target | Return vs spot |
|---|---|---|---|
| Structural — AI Disruption / SaaS De-Rate | 20% | $50.50 | -53% |
| Enterprise-Spend Recession | 17% | $85.10 | -20% |
| Base — Seat + Retention Growth | 35% | $118 | +11% |
| Growth — AI Monetization / Platform | 20% | $160 | +50% |
| Bull — Re-Rate | 8% | $203 | +89% |
| Probability-Weighted (PWEV, after SBC dilution) | — | $111 | +4% |
SBC charge: scenario targets are gross per-share prices; the PWEV is reduced by one year of stock-based-compensation dilution (3.0% of shares, on SBC ≈ 11% of revenue), trimming the gross PWEV of $114 to $111 (-2.9%). SBC is charged once, as dilution — never also deducted from FCF.
Scenario rationale — the driver path behind every target:
- Structural — AI Disruption / SaaS De-Rate (20%, $50.50). Structural impairment — AI disruption / SaaS de-rate: earnings AND the multiple compress together. Target sits below the 52-week low by construction.
- Enterprise-Spend Recession (17%, $85.10). Cyclical downturn — software/SaaS spend + net retention + AI monetization vs AI disruption weakens for 1–2 years before normalising.
- Base — Seat + Retention Growth (35%, $118). Mid-cycle — normalised software/SaaS spend + net retention + AI monetization vs AI disruption; disciplined capital allocation; steady returns.
- Growth — AI Monetization / Platform (20%, $160). Upside — AI monetization + platform expansion lifts earnings above mid-cycle; the multiple expands modestly.
- Bull — Re-Rate (8%, $203). Upside tail — sustained tight conditions or a structural re-rate on AI monetization + platform expansion.
Valuation Triangulation
Three weighted anchors — an intrinsic dcf, a scenario-weighted pwev and a monte carlo median (student-t + regime switching) — read them with their basis in mind. The Monte Carlo, the scenario PWEV, any DCF's exit-multiple terminal and any peer re-rate key off a market multiple, so they are not independent; only a DCF's explicit-period cash flows are multiple-free, and its terminal usually carries most of its value. The discipline is to read the spread, not to treat three numbers as three independent votes.
| Method | Basis | Fair Value | vs Spot | Weight in this name's blend |
|---|---|---|---|---|
| Monte Carlo median (Student-t + regime) | multiple | $102 | -5% | 20% (declared 15%) |
| Peer EV/Revenue re-rate | multiple | $19.19 | -82% | 0% — cross-check only |
| Scenario PWEV | multiple | $111 | +4% | 33% (declared 25%) |
| DCF (5-year + exit-multiple terminal) | cash flow + terminal × | $85.16 | -20% | 47% (declared 35%) |
| Triangulated (weighted) | — | $97.05 | -9% | 100% |
The house blend DECLARES five anchor weights — DCF 35%, scenario PWEV 25%, Monte Carlo 15%, sum-of-parts 15%, peer re-rate 10%. For this name sum-of-parts, peer P/E re-rate are not computed, so 25% of the declared weight is redistributed across the anchors that exist — which is why the weights above differ from the declared ones. The fair value is unaffected by this disclosure; the blend has always worked this way. The company-lever row in the Sensitivity section is an illustrative EBIT × multiple value, not a sum-of-parts anchor.
Peer EV/Revenue re-rate — 0% weight: it duplicates the peer-multiple information already carried by the Peer P/E anchor while ignoring margin mix; weighting both would double-count the peer view. Shown as a cross-check.
Monte Carlo — the outcome distribution
10,000 paths, Student-t shocks (fat tails) with a regime-switching overlay. The median lands at $102 and 45% of paths finish above spot. The variance decomposition shows the p/e multiple is the dominant swing factor (73% of variance). Value is a multiple bet: fundamentals move the answer far less than the rating does.
DCF — explicit-period cash flows with an exit-multiple terminal
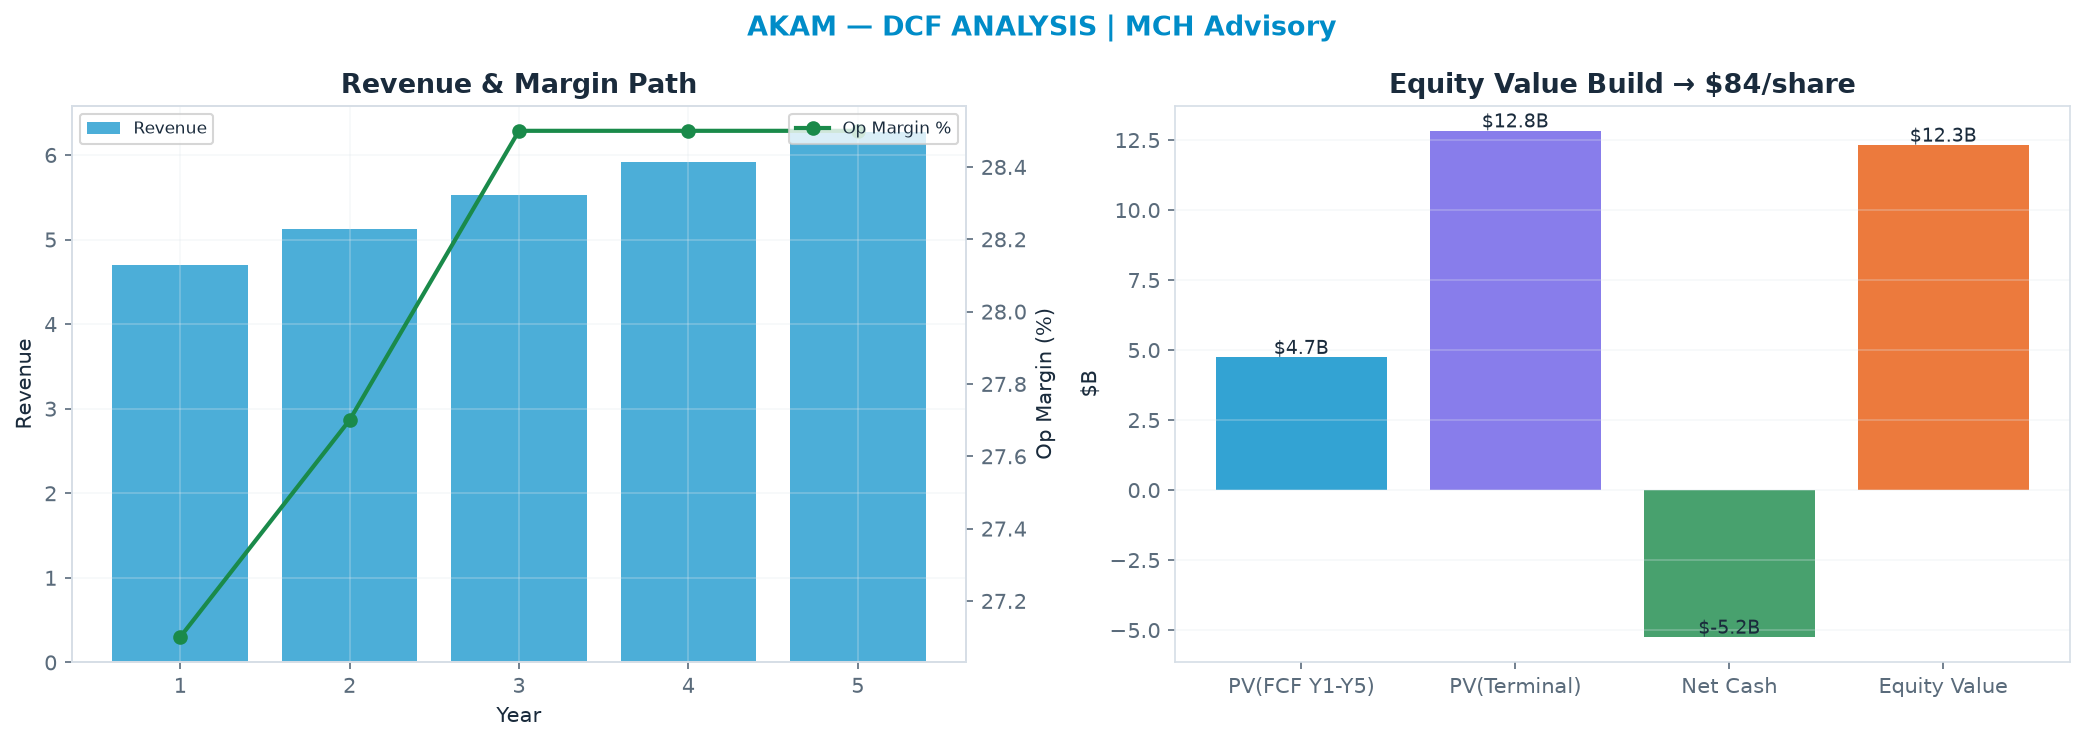
A 5-year cash-flow path discounted at a WACC of 9.0%, plus a terminal value of final-year FCF × 14.0x — a terminal multiple equal to 0.85 × the base multiple that the Monte Carlo and the scenario tree also use → $85.16. The terminal value is 73% of enterprise value, so this anchor moves with the multiple assumption. The heaviest anchor in this blend (47%); because its terminal is a market multiple, it is not independent of the multiple-driven anchors.
Peer benchmarking — relative value
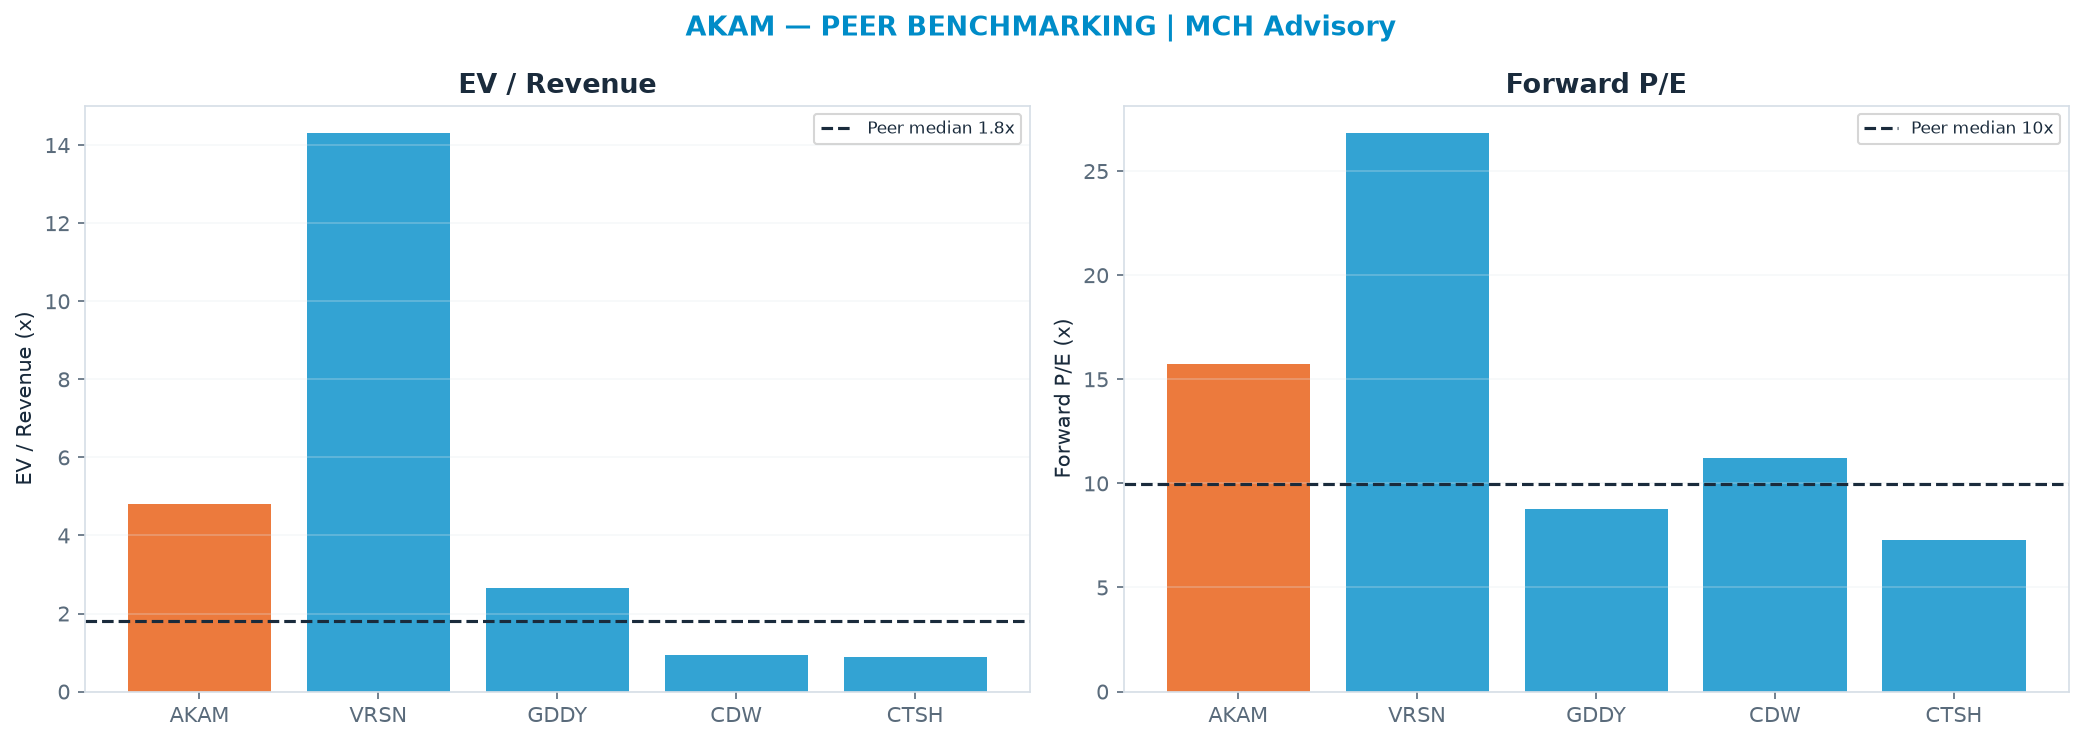
Against the peer cohort, re-rating to the peer-median EV/Revenue multiple implies $19.19; the peer-median forward P/E is 10.0x, but the engine carries no P/E-implied price for this name (fewer than three same-sub-industry peers carry a forward multiple). A premium is only justified by superior growth/margins; otherwise it is multiple risk. Excluded from the weighted blend — shown only as a market cross-check.
Across all anchors the spread is 90% of the median — wide (genuine disagreement — the blend carries low valuation confidence).
Sensitivity
DCF/share — WACC × terminal multiple
| WACC \ Term× | 9.8x | 11.9x | 14.0x | 16.1x | 18.2x |
|---|---|---|---|---|---|
| 7.0% | $66.82 | $81.12 | $95.43 | $110 | $124 |
| 8.0% | $62.85 | $76.50 | $90.16 | $104 | $117 |
| 9.0% | $59.09 | $72.12 | $85.16 | $98.20 | $111 |
| 10.0% | $55.51 | $67.97 | $80.42 | $92.88 | $105 |
| 11.0% | $52.12 | $64.02 | $75.92 | $87.83 | $99.73 |
DCF/share — revenue CAGR Δ × model op-margin Δ (Δ applied to the DCF's house margin path)
| CAGRΔ \ MgnΔ | -3.0pp | -1.5pp | +0.0pp | +1.5pp | +3.0pp |
|---|---|---|---|---|---|
| -3.0pp | $58.70 | $64.59 | $70.48 | $76.36 | $82.25 |
| -1.5pp | $65.09 | $71.36 | $77.62 | $83.89 | $90.16 |
| +0.0pp | $71.82 | $78.49 | $85.16 | $91.83 | $98.50 |
| +1.5pp | $78.91 | $86.01 | $93.10 | $100 | $107 |
| +3.0pp | $86.38 | $93.92 | $101 | $109 | $117 |
Tornado — DCF/share swing by driver (widest first)
| Driver | Low | High | Swing |
|---|---|---|---|
| Revenue CAGR ±3pp | $70.00 | $101 | $31.00 |
| Model op margin ±3pp | $72.00 | $99.00 | $27.00 |
| Terminal × ±15% | $72.00 | $98.00 | $26.00 |
| Capex intensity ±15% | $73.00 | $98.00 | $25.00 |
| WACC ±1pp | $80.00 | $90.00 | $10.00 |
Company lever — value at the base multiple vs Enterprise Software multiple (base 17.0x)
| Multiple | 11.9x | 14.4x | 17.0x | 19.5x | 22.1x |
|---|---|---|---|---|---|
| Value at the base multiple (EBIT × multiple; illustrative, not a blend anchor) | $55.00 | $74.00 | $93.00 | $112 | $132 |
Illustrative: segment EBIT × multiple, plus net cash, over basic shares — it does not enter the triangulated fair value.
Peer Quality & Weighting
| Peer | Fwd P/E | Growth | Op margin | Quality | Weight cap |
|---|---|---|---|---|---|
| VRSN | 26.8× | 10% | 68% | broad | 25% |
| GDDY | 8.8× | 10% | 25% | segment | 50% |
| CDW | 11.2× | 5% | 7% | segment | 50% |
| CTSH | 7.3× | 5% | 16% | segment | 50% |
Quality-weighted forward P/E: 11.6× (simple median 10.0×). Direct peers count 100%, segment 50%, broad 25%.
Historical-range cross-check: 52-week range $70.82–$165, centre $108 (+1% vs spot); spot sits at the 38th percentile of the range. Low-weight mean-reversion cross-check, not a fundamental anchor.
Risk / Reward & Margin of Safety
| Metric | Value |
|---|---|
| Upside to triangulated FV (FV ÷ price − 1) | $97.05 (-9% vs spot · triangulated FV) |
| Downside to lowest scenario (Structural — AI Disruption / SaaS De-Rate) | $50.50 (-53% vs spot · bear scenario) |
| Reward-to-risk ratio | withheld — the triangulated FV is at or below spot, so there is no reward leg to divide by the risk leg |
| Discount to fair value (1 − price ÷ FV) | -10% |
| P(price > spot) — Monte Carlo | 45% |
That ratio is (triangulated FV ÷ price − 1) ÷ (1 − 'Structural — AI Disruption / SaaS De-Rate' target ÷ price). 'Structural — AI Disruption / SaaS De-Rate' ($50.50, probability 20%) is the lowest-target scenario in the tree, taken gross of SBC dilution. With a leg missing the ratio is withheld rather than computed from a magnitude. Bull case (Bull — Re-Rate): $203.
Company Overview & Business Model
Akamai Technologies Inc — TECHNOLOGY · SOFTWARE - INFRASTRUCTURE. Akamai Technologies, Inc. is a global content delivery network (CDN), cybersecurity, and cloud service company, providing web and Internet security services.
Company description as supplied by Alpha Vantage; not checked against the company's filings.
How it makes money.
| Segment | Rev mix | Growth | Model op margin† | Key driver |
|---|---|---|---|---|
| Enterprise Software | 100% | +10% | 25% | software/SaaS spend + net retention + AI monetization vs AI disruption |
† Model margin = gross margin − the opex ratio calibrated so the Monte Carlo median EPS meets the EPS target; it is not a reported operating margin.
Reported operating margin (GAAP): 14.9% for the fiscal year ended 2025-12-31; 11.8% TTM to 2026-06-30 (Alpha Vantage INCOME_STATEMENT).
Edge. Narrow moat. Authored moat rationale withheld pending re-authoring.
Revenue-Segment Breakdown
The company-specific drivers behind the valuation — each segment carries its own growth, margin, multiple and capex intensity. (Tags: FACT reported · ESTIMATE from disclosures · INFERENCE judgment.)
| Segment | Revenue | Mix | Growth | Model op margin† | Model EBIT | Multiple | Capex % | Tag |
|---|---|---|---|---|---|---|---|---|
| Enterprise Software | $4.3B | 100% | 10% | 25% | $1.1B | 17.0x | 3% | ESTIMATE |
| † Model EBIT = revenue × the model margin, i.e. gross margin less the opex ratio the calibration solved for to meet the EPS target — not the company's reported operating income. |
For comparison, the company's reported GAAP operating margin was 14.9% for the fiscal year ended 2025-12-31; 11.8% TTM to 2026-06-30 (Alpha Vantage INCOME_STATEMENT).
Named Exposures
Demand & pricing cycle (FACT/ESTIMATE)
| Dimension | Assessment |
|---|---|
| driver | software/SaaS spend + net retention + AI monetization vs AI disruption |
| net_debt_or_cash_b | -4.94 |
Capital intensity & shareholder returns (ESTIMATE)
| Dimension | Assessment |
|---|---|
| capex_pct_revenue | 0.03 |
| div_yield | — |
Structural risk vs optionality (INFERENCE)
| Dimension | Assessment |
|---|---|
| downside | AI disruption / SaaS de-rate |
| upside | AI monetization + platform expansion |
Balance Sheet & Liquidity
| Metric | Value |
|---|---|
| Net debt | $5.7B — highly levered |
| Net debt / EBITDA | 5.30x |
| Interest coverage (EBIT / interest) | 20.4x |
| Current ratio | 2.29x |
| Lease obligations | $1.6B |
| Cash & ST investments | $1.2B |
Balance-sheet data as of 2025-12-31 (Alpha Vantage).
Capital Allocation
| Metric | Value |
|---|---|
| Free cash flow | $0.7B |
| Buybacks / dividends | $0.8B / $0.0B |
| Total shareholder yield | 5.1% |
| Payout as % of FCF | 114.4% |
| Reinvestment (capex / OCF) | 54.0% |
| SBC as % of FCF | 65.7% |
| Allocation stance | returning more than FCF (balance-sheet funded) |
Free-Cash-Flow Quality
| Metric | Value |
|---|---|
| FCF margin | 16.3% |
| FCF conversion (FCF / net income) | 154.6% |
| FCF yield | 4.5% |
| Capex intensity (capex / revenue) | 19.1% |
| FCF − SBC (diagnostic) | $0.2B |
| Capex split (maint / growth) | 55% / 45% — Network/infrastructure-heavy for a software name: capex sustains the edge server footprint (maintenance) and funds the Connected Cloud compute build-out (growth). The elevated growth share reflects the capital cost of the cloud-compute pivot. |
Accounting quality: SBC 11% of revenue; cash conversion (OCF/NI) 336% — cash-backed.
Competitive Moat
Moat sources:
- Globally distributed edge server footprint (peering/last-mile proximity) - hard to replicate at scale
- Security switching costs (App & API Protector, Guardicore microsegmentation embedded in customer workflows)
- Enterprise relationships and compliance/latency-sensitive delivery contracts
- Eroding moat in core delivery - commoditised, price-competed against Cloudflare/Fastly and hyperscaler CDNs
Earnings-Call Disconfirmation & Sentiment
Derived signals from the MCH market-data store (Alpha Vantage transcripts + news). Quantitative tone only — a disconfirmation flag, not a substitute for reading the call.
Management vs analyst tone (2026Q2): management +0.53 vs analyst floor +0.07 → delta +0.46 (n=23 mgmt / 16 Q&A; 59th pctile across the S&P book, z +0.3).
Flag: TYPICAL — management-vs-analyst tone within the normal cross-sectional range.
| Quarter | Mgmt | Analyst | Delta |
|---|---|---|---|
| 2026Q2 | +0.53 | +0.07 | +0.46 |
| 2026Q1 | +0.44 | +0.03 | +0.40 |
| 2025Q4 | +0.60 | +0.46 | +0.14 |
| 2025Q3 | +0.49 | +0.34 | +0.15 |
News (last 365d, 1453 articles): avg ticker sentiment +0.18 (bullish 30% / bearish 5%)
Consensus & Market Expectations
| Reference | Value |
|---|---|
| Street target (mean) | $159 (+48% vs spot · street) |
| House target | $110 (-31.0% vs street) |
| Sell-side coverage | 24 analysts (SB 5 / B 10 / H 8 / S 1 / SS 0; net score 0.4) |
| Consensus FY EPS | $6.64 (reference only — house values on EV/EBITDA) |
| Consensus FY revenue | $4.5B; house above (+4.7%) |
_Consensus figures: Alpha Vantage sell-side aggregates. Where the house view sits materially above or below the street, the divergence is itself a datum — see the thesis.
Catalyst Calendar
- 2026-11-05 (~27d) — Quarterly earnings — est. EPS $0.92 (AV EARNINGS_CALENDAR)
- 2026-12-01 (~53d) — Delivery-segment revenue-decline inflection / renewal cohort pricing (authored)
- 2027-02-15 (~129d) — Security platform (API/Guardicore) product cycle and cross-sell metrics (authored)
Forecast Track Record
- EPS surprise: beat 75% of the last 8 quarters; average surprise +2.5%.
Catalyst Timeline
6 catalysts in the next 90 days (of 14 tracked). Importance 1–3; confidence 0–1.
| When | Catalyst | Type | Importance | Confidence |
|---|---|---|---|---|
| 2026-10-14 (in 2d) | September CPI | macro | ●● | 0.8 |
| 2026-10-28 (in 16d) | FOMC rate decision + press conference | macro | ●● | 0.8 |
| 2026-11-05 (in 24d) | Quarterly earnings | earnings | ●●● | 0.95 |
| 2026-12-01 (in 50d) | Delivery-segment revenue-decline inflection / renewal cohort pricing | authored | ● | 0.7 |
| 2026-12-09 (in 58d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2026-12-18 (in 67d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
| 2027-01-27 (in 107d) | FOMC rate decision + press conference | macro | ●● | 0.8 |
| 2027-02-15 (in 126d) | Security platform (API/Guardicore) product cycle and cross-sell metrics | authored | ● | 0.7 |
| 2027-03-17 (in 156d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2027-03-19 (in 158d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
| 2027-04-28 (in 198d) | FOMC rate decision + press conference | macro | ●● | 0.8 |
| 2027-06-09 (in 240d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2027-06-18 (in 249d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
| 2027-09-17 (in 340d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
_Sources: extended.catalysts, data/catalysts/
Regulatory & Legal Risk
| Issue | Probability | Valuation sensitivity | Horizon |
|---|---|---|---|
| Data-privacy / cross-border data-transfer and sovereignty rules affecting edge/CDN and cloud placement | medium (~40%) | low - largely a compliance and architecture cost, ~2-3% of FV | 12-24m |
| Cybersecurity incident-disclosure and critical-infrastructure regulation raising security-product demand and compliance obligations | medium (~45%) | low - net neutral to modestly positive (demand tailwind offsets compliance cost), ~2% of FV | 12-24m |
Probabilities and sensitivities are analyst estimates, not market-implied.
Scenario Macro & Key Risks
| Scenario | Macro assumption | Key risk |
|---|---|---|
| Structural — AI Disruption / SaaS De-Rate | Hyperscalers and AI-native edge/security offerings commoditise Akamai's differentiation while the software/SaaS complex de-rates, compressing both growth and multiple. | Delivery decline accelerating faster than security+compute can grow, turning blended growth negative and forcing a market-or-below multiple. |
| Enterprise-Spend Recession | A broad enterprise IT-budget pullback slows security-seat expansion and delays compute migration for 1-2 years. | Discretionary security and compute spend being deferred just as delivery keeps shrinking, exposing the lack of a growth cushion. |
| Base — Seat + Retention Growth | Security grows double-digit and compute ramps steadily, roughly offsetting a managed delivery decline for flattish-to-modest total growth. | The base already assumes the offset works; a modest miss on either security retention or compute ramp tips the thesis negative. |
| Growth — AI Monetization / Platform | Connected Cloud compute and AI-inference-at-the-edge monetise the network footprint, lifting blended growth into high single digits. | Competing directly with far-larger hyperscalers on compute where Akamai lacks scale, breadth of services, and capital firepower. |
| Bull — Re-Rate | Security-led growth reaccelerates and the market re-rates Akamai as a platform-security compounder rather than a legacy CDN. | A re-rate requires the market to look past a still-declining delivery segment that remains a large share of revenue. |
Decision Rules (Machine-Checked)
Stance: Hold — 0 bullish / 0 bearish / 1 caution rules triggered of 6 evaluable (0 lacked data).
| Rule | Condition | Observed | Triggered |
|---|---|---|---|
| R1-valuation-stretch | expected return vs fair value < -12 (upside_pct) |
2.55 | no |
| R2-valuation-opportunity | expected return vs fair value > 15 (upside_pct) |
2.55 | no |
| R3-street-revisions | street net rating stance < -0.25 (extended.consensus.street_score) |
0.4 | no |
| R4-earnings-quality | cash conversion of earnings < 80 (extended.accounting_quality.cash_conversion_pct) |
336.1 | no |
| R5-technical-breakdown | price vs 200-day SMA < 0.85 (technicals.sma_200) |
0.95 | no |
| R6-vol-regime-shift | IV/RV vol-risk premium > 1.4 (options_overlay.iv_rv) |
1.41 | YES |
Machine-checked rules over disclosed inputs. The authored falsification triggers elsewhere in this report are analyst judgment and are NOT evaluated here. The stance is what the model's own rules read on this name; it does not modify the published research rating, and it is not personal financial advice.
Reasons the Thesis Could Fail (Falsifiable)
Pre-registered signals that would break the thesis — each polices a specific scenario boundary and is checked at every earnings update:
- Total revenue growth (YoY) < 0.06 (2 consecutive prints). (rationale withheld pending re-authoring — frozen figure or verdict)
- Security revenue growth (YoY) < 0.08 (2 consecutive prints). (rationale withheld pending re-authoring — frozen figure or verdict)
- Delivery revenue growth (YoY) < -0.12 (2 consecutive prints). (rationale withheld pending re-authoring — frozen figure or verdict)
- Operating margin (engine basis) < 0.244 (2 consecutive prints). (rationale withheld pending re-authoring — frozen figure or verdict)
- Capex as % of revenue > 0.24 (2 consecutive prints). (rationale withheld pending re-authoring — frozen figure or verdict)
Fact / Inference / Speculation
- FACT: Spot $107; 52-week range $70.82–$165; engine rating HOLD; house target $110 (+3%). (source: Alpha Vantage 2026-10-09, 12 October 2026)
- INFERENCE: Triangulated FV $97.05 (-9% vs spot · triangulated FV); the rating tracks the Monte-Carlo + scenario-PWEV core; the DCF anchor sits below the multiple-discipline core.
- SPECULATION: At current prices the embedded bet is that the market keeps paying the current multiple through the capex cycle — a regime call the engine cannot verify from fundamentals alone.
Conviction Score
Research Conviction measures the strength and quality of the research setup — input coverage, financial quality, valuation support, process agreement. It is NOT the probability that the recommendation succeeds; the forecast track record section is the evidence on that.
50.7/100 (confidence band 38.6–62.7), 20th percentile of 893 covered names (as of 2026-10-10). Weighted composite under config ros-1.20.0 — every component and its inputs below.
| Component | Score (0–100) | Weight | Inputs |
|---|---|---|---|
| business quality | 46 | 15% | extended.fcf_quality.fcf_margin_pct, extended.balance_sheet.net_debt_to_ebitda, extended.accounting_quality.cash_conversion_pct |
| financial strength | 32 | 10% | extended.balance_sheet.net_debt_to_ebitda, extended.balance_sheet.interest_coverage |
| valuation | 52 | 15% | upside_pct |
| growth | 63 | 10% | reconciliation.ttm_revenue_billions, reconciliation.fy_guide_revenue_billions |
| earnings visibility | 75 | 10% | extended.forecast_accuracy.eps_surprise.beat_rate_pct |
| moat | 55 | 10% | enrichment.moat.rating |
| technical trend (heuristic — no validation record; weight change reserved for AM-060) | 24 | 10% | technicals.rsi, technicals.sma_50, technicals.sma_200 |
| macro tailwinds | — | 10% | industry_context.house |
| risk profile | 58 | 10% | monte_carlo.prob_above_current, monte_carlo.p10, monte_carlo.p90, monte_carlo.median |
Missing inputs (macro tailwinds) are excluded and the remaining weights renormalised; the confidence band widens accordingly.
Score history: 51.3 → 51.5 → 51.4 → 51.2 → 51.2 → 51.7 → 52.5 → 50.7.
Probability-Weighted Return Profile
Horizon: 1 year — at this horizon CAGR equals total return by definition. Expected values are the probability-weighted sums over the full scenario set below.
| Scenario | Probability | Target | Total return | Contribution |
|---|---|---|---|---|
| Structural — AI Disruption / SaaS De-Rate | 20% | $50.50 | -52.8% | -10.6pp |
| Enterprise-Spend Recession | 17% | $85.10 | -20.4% | -3.5pp |
| Base — Seat + Retention Growth | 35% | $118 | +10.6% | +3.7pp |
| Growth — AI Monetization / Platform | 20% | $160 | +49.6% | +9.9pp |
| Bull — Re-Rate | 8% | $203 | +89.4% | +7.2pp |
| Aggregate | Value |
|---|---|
| Expected return (gross, 1y) | +6.8% |
| Expected return net of SBC dilution | +3.7% |
| Outcome dispersion (σ, from MC p10–p90) | 43.3% |
| Expected Sharpe (rf 4%) | 0.06 |
| Downside expectation (prob-weighted loss branches) | -14.0% |
The gross expected return is the probability-weighted scenario return (it reconciles to the gross PWEV); the diluted figure applies the SBC share-count charge and matches the published PWEV-based target.
Expected Alpha
Expected return minus the return this name is REQUIRED to deliver for its risk (1-year horizon). Constants are pre-registered (preregistered-static (amendment #2, 2026-07-29); not fitted to MCH outcomes).
| Component | Value |
|---|---|
| Expected return (gross, 1y) | 6.8% |
| Risk-free rate | 4.49% (1y proxy (3m/2y midpoint; AV lacks a 1y tenor), as of 2026-10-08) |
| Beta (shrunk, 1y vs SPY) | 1.21 (as of 2026-10-09) |
| Equity risk premium | 4.5% |
| Required return | 10.0% |
| Expected alpha | -3.2% |
| Alpha per unit risk (EA/σ) | -0.07 |
A negative expected alpha does not change the rating — it says the expected return does not clear the risk-adjusted hurdle at today's price. Rating mechanics are unchanged by this section.
Probability Cross-Checks
Not authoritative. The scenario probabilities in this report are AUTHORED — a judgement about how the world might go, not a measurement. Nothing below modifies them, the target, the rating or any position size. These checks ask only whether anything outside our own model agrees with us; where it does not, that is information for the reader, not a correction we have quietly applied.
| Cross-check | Ours | Comparator | Reading |
|---|---|---|---|
| Scenario spread vs options market | 41.9% (1σ) | 58.9% implied | broadly consistent with the market's implied uncertainty |
| Mass above spot: scenarios vs our own MC | 63.0% | 45.4% | the two expressions of our own view agree |
| Realised scenario frequency | 58 dated anchors | — | 58 dated anchors available; realised-vs-prior comparison is now meaningful. |
Authored set: 5 scenarios, probabilities summing to 1.0, mean target $114.18.
Factor Exposures
Cross-sectional percentiles over 928 covered names (style scores sector-demeaned; thematic = return-beta to the theme's proxy ETF). 50 = estate median.
| Style | Percentile | Theme | Percentile | |
|---|---|---|---|---|
| Growth | 54 | AI | 88 | |
| Value | 71 | Cloud | 88 | |
| Quality | 8 | Semis | 86 | |
| Momentum | 49 | Consumer | 40 | |
| Low-Vol | 44 | Rates | 89 | |
| USD | 22 | |||
| Energy | 73 |
Market interaction: correlation vs SPY +0.37, vs QQQ +0.37 (trailing ~1y daily returns).
Rating Bridge
Rating = HOLD because:
- Probability-weighted scenario value implies +4% vs spot
- Monte Carlo median implies -5% vs spot
- DCF fair value (exit-multiple terminal) implies -20% vs spot
- Bear case (Structural — AI Disruption / SaaS De-Rate) downside is -53% vs spot
- Net: the valuation anchor itself sits 9.3% below spot, so there is no reward leg to weigh against the bear case and the reward-to-risk ratio is withheld rather than computed off a negative upside. The rating is not asymmetric enough for a Buy and not impaired enough for a Sell — hence Hold.
Model Appendix
DCF — line items
| Year | Revenue | Op income (house path) | − Capex | + D&A | FCF | PV(FCF) |
|---|---|---|---|---|---|---|
| FY+1 | $5B | $1B | $1B | $1B | $1B | $1B |
| FY+2 | $5B | $1B | $1B | $1B | $1B | $1B |
| FY+3 | $6B | $2B | $1B | $1B | $1B | $1B |
| FY+4 | $6B | $2B | $1B | $1B | $1B | $1B |
| FY+5 | $6B | $2B | $1B | $1B | $1B | $1B |
| Terminal | — | — | — | — | $1B × 14.0x | $13B |
FCF is bridged: NOPAT + D&A − Capex − ΔNWC (capex intensity 3% of revenue, weighted from the segments) — not a single conversion fudge.
WACC 9.0% · Σ PV(FCF) $5B + PV(terminal) $13B = EV $17B; − net debt $4.9B → equity $12B ÷ diluted shares $0.15B = $85.16/share (exit-multiple terminal).
- Gordon terminal → $96.14/share — a single-point perpetual-growth cross-check at g = 2.5% (one growth rate, not a range; it is not in the blend).
- Incremental ROIC on the forecast capex ≈ 9% vs WACC 9.0% → above WACC — the build is value-creative.
Peer set
| Peer | EV/Rev | Fwd P/E | Growth | Op margin |
|---|---|---|---|---|
| VRSN | 14.3x | 26.8x | 10% | 68% |
| GDDY | 2.7x | 8.8x | 10% | 25% |
| CDW | 0.9x | 11.2x | 5% | 7% |
| CTSH | 0.9x | 7.3x | 5% | 16% |
| Median | 1.8x | 10.0x | — | — |
Implied prices at the peer medians: EV/Rev → $19.19 (no P/E-implied price — fewer than three same-sub-industry peers carry a forward multiple).
Weighted fair-value math
| Anchor | Value | Weight | Contribution |
|---|---|---|---|
| DCF | $85.16 | 47% | $39.74 |
| Scenario PWEV | $111 | 33% | $36.97 |
| Monte Carlo median | $102 | 20% | $20.34 |
| Triangulated | — | 100% | $97.05 |
Assumption Register
| Assumption | Value | Used in | Source |
|---|---|---|---|
| WACC | 9.0% | DCF discount rate | estimate (CAPM) |
| Terminal multiple | 14× | DCF exit value | house rule (0.85 × base multiple) |
| Terminal growth | 2.5% | Gordon cross-check (single point) | estimate |
| SBC dilution | 3.0%/yr | PWEV, MC, DCF (charged once) | estimate (from SBC/rev) |
| EPS basis | consensus forward EPS (broker-adjusted, non-GAAP) | all forward P/E & scenario multiples | definition |
Sensitivity-ranked drivers (widest fair-value swing first): Revenue CAGR ±3pp (31.0); Model op margin ±3pp (27.0); Terminal × ±15% (26.0); Capex intensity ±15% (25.0); WACC ±1pp (10.0).
Inputs, Sources & Confidence
Every load-bearing input, labelled by type and confidence. (reported fact · company guidance · consensus estimate · market data · house estimate · inference.)
| Input | Value | Type | Source | Confidence | Used in |
|---|---|---|---|---|---|
| Revenue TTM | $4.3B | reported fact | 10-K/10-Q via AV | High | Forecast base, EV/Rev |
| FY+1 guided revenue | $4.7B | company guidance | Company guidance | Medium | Forecast, SoP |
| FY+1 guided EPS | $6.6421 | company guidance | Company guidance | Medium | Forward P/E, scenarios |
| Consensus FY EPS | $6.6395 | consensus estimate | Sell-side consensus via AV | Medium | Variant perception |
| Diluted shares | 0.146B | reported fact | 10-K via AV | High | Market cap, per-share |
| Net debt / cash | $5.722B | reported fact | Balance sheet via AV | High | EV, DCF equity bridge |
| WACC | 9.0% | house estimate | CAPM (beta/rf) | Medium | DCF discount rate |
| Terminal multiple | 14× | house estimate | House rule: 0.85 × the base multiple (shared with the Monte Carlo) | Medium | DCF exit value |
| Terminal growth | 2.5% | house estimate | Long-run GDP+ | Medium | Gordon cross-check (single point, not in the blend) |
| SBC dilution | 3.0%/yr | house estimate | From SBC/revenue | Medium | PWEV, MC, DCF (charged once) |
Research Provenance
| Field | Value |
|---|---|
| Quantitative engine | mch_stock_engine v2.0 |
| Research OS config | ros-1.20.0 |
| Analysis as-of | 2026-10-12 (prices 2026-10-09) |
| Narrative authorship | claude-opus-5 · Claude Code, supervised, drafted 2026-08-16 |
| Human review | Marinus 2026-08-16 |
| Evidence | 8/8 load-bearing inputs sourced; 13/14 mandated claims cited |
| QA | scanned post-emit by the document-QA layer; the publication label (Draft / Research / Decision-level) is stamped on the published page, not authored here |
Load-Bearing Assumptions
DCF: WACC 9.0%, terminal multiple 14×, FY+5 revenue $6B. Triangulation leans 47% on DCF, 33% on PWEV, 20% on the Monte Carlo median.
Appendix & audit trail — source log, data provenance, disclosures
Source Log
| Source | Type | Date | Used for | Reference |
|---|---|---|---|---|
| Alpha Vantage — GLOBAL_QUOTE / OVERVIEW | market data | 2026-10-09 | Price, market cap, EV, forward P/E | Alpha Vantage 2026-10-09 |
| MCH engine — trailing 52 weeks of daily bars | derived | 2026-10-09 | 52-week range (intraday high and low over the trailing year of the stock's own daily bars) | trailing 52 weeks of own daily bars (intraday high/low, 2025-10-10 to 2026-10-09, 251 sessions) |
| Company income statement (10-K / 10-Q) via Alpha Vantage | reported fact | 2026-10-09 | Revenue, gross/operating margin, EBIT, interest expense | INCOME_STATEMENT / latest annual |
| Company balance sheet (10-K / 10-Q) via Alpha Vantage | reported fact | 2026-10-09 | Cash, debt, net debt, leases, equity, coverage | BALANCE_SHEET / latest annual |
| Company cash-flow statement (10-K / 10-Q) via Alpha Vantage | reported fact | 2026-10-09 | Operating cash flow, capex, FCF, buybacks, dividends, SBC | CASH_FLOW / latest annual |
| Company earnings releases via Alpha Vantage | reported fact | 2026-10-09 | Reported EPS, surprise history | EARNINGS / quarterly |
| Sell-side consensus via Alpha Vantage | consensus estimate | 2026-10-09 | Forward revenue/EPS consensus, analyst count | EARNINGS_ESTIMATES |
| Earnings calendar via Alpha Vantage | market data | 2026-10-09 | Next earnings date, catalyst timing | EARNINGS_CALENDAR |
| Company guidance | company guidance | 2026-10-09 | FY guided revenue / non-GAAP EPS basis | company guidance / earnings call |
| MCH segment model (from filings & disclosures) | house estimate | 2026-10-09 | Segment revenue and multiple; model margin = gross margin − the calibrated opex ratio (not a reported margin) | company_context (authored, tagged) |
| MCH qualitative analysis | inference | 2026-10-09 | Moat, regulatory risk, scenario macro, catalysts | company_context enrichment (authored) |
| MCH investment thesis & falsification triggers | house estimate | 2026-10-09 | Thesis, anti-thesis, thesis-break signals | authored §5.3 |
Citation coverage: 13/14 mandated claims sourced. Filing URLs are not available via the market-data provider; company statements are cited as 10-K/10-Q via Alpha Vantage.
Data Sources
- Prices, fundamentals, options chain, earnings — Alpha Vantage.
- Company filings (10-K / 10-Q) — SEC filings via EDGAR.
Disclosures & Limitations
This report is for informational and research purposes only. It is not personal financial advice and does not consider any investor's objectives, financial situation, risk tolerance, tax position, or liquidity needs.
- This report is produced by the MCH Analysis quantitative research engine — valuation, scenarios, Monte Carlo and the decision layer are generated systematically from the disclosed inputs and the archetype/industry driver sets, and reviewed rather than written name-by-name. Every figure reconciles to the appendix and every score exposes its inputs.
- No suitability assessment has been performed for any individual.
- Market data may be delayed or inaccurate; figures are as of the analysis date.
- Model outputs (fair values, targets, scenario probabilities) are estimates and may be wrong.
- Forecasts are uncertain; past performance is not indicative of future returns.
- The author or publisher may hold positions in securities mentioned.
- Users should verify information against primary sources (company filings) before acting.
- Investing involves risk of loss; there is no guarantee any target price is achieved.
- Ratings follow a defined research methodology (12-month expected-return thresholds), not individual circumstances.