Investment Committee Summary
| Rating | HOLD |
| Internal 5-tier | HOLD |
| Classification · conviction | mature cash generator · medium |
| Evidence | 7/8 load-bearing inputs sourced — missing: Capex |
| Triangulated fair value | $70.78 (-9% vs spot · triangulated FV) |
| 12-mo scenario PWEV | $77.40 (-0% vs spot · 12m PWEV) |
| Next catalyst | 2026-10-22 — Quarterly earnings |
| Primary thesis-break | Organic revenue growth / order backlog < flat-to-negative for two consecutive quarters (2 consecutive prints) |
Decision detail — rating tables & Research OS strip
Rating: HOLD
Internal 5-tier: HOLD · mature cash generator · analyst conviction: medium
| Metric | Value |
|---|---|
| Current Price | $77.57 |
| Triangulated Fair Value | $70.78 (-9% vs spot · triangulated FV) |
| 12-mo Scenario PWEV | $77.40 (-0% vs spot · 12m PWEV) |
| Forward P/E | 12.0x |
| Market Cap | $13B |
| 52-Week Range | $51.75–$79.07 (high/low reconstructed from the stock's own adjusted-close history — the vendor's recorded range was stale) |
EPS basis for the forward P/E and all scenario multiples: consensus forward EPS (broker-adjusted, non-GAAP).
Methodology: Valuation triangulated across four weighted anchors — an intrinsic DCF, a scenario-weighted PWEV, a Monte Carlo median (Student-t + regime switching) and a peer P/E re-rate. Anchors that share a market multiple are not independent evidence and are weighted as one view. Figures reconciled to Alpha Vantage 2026-08-20. Each chart below sits with the part of the thesis it evidences.
General research for a skeptical institutional reader. Not personalised investment advice. The risk framework below is an illustrative model construct, not an instruction to trade. Figures as of the analysis date; verify before acting.
Decision Support — Research OS jump to detail ↓
| Research conviction | Exp. return (1y) | Rules stance | Next catalyst |
|---|---|---|---|
| 70.2/100 (92nd pct) | -0% 1yr expected | Hold | 58d — Quarterly earnings |
Full breakdown — conviction components, position sizing, probability-return distribution, decision rules, factor & portfolio interaction, options intelligence and the catalyst timeline — in the Decision Support sections below. Model output for research; not individualised advice.
📎 Download the full model (Excel) — DCF line items, scenarios, sensitivity, assumptions, and extended fundamentals.
Recommendation: HOLD
Balanced: triangulated fair value $70.78 (-9% vs spot); the outcome hinges on P/E Multiple. The debate is P/E Multiple — fundamentally a multiple/regime call.
Investment Thesis
Webster Financial is the holding company for a national commercial bank serving individuals, families and businesses across the United States. The engine carries its spread-and-fee margin near 51% — a high figure that is either a durable funding advantage or a mix that will normalise, and deciding which is the whole exercise. No net-cash figure is shown, correctly, because for a lender the balance sheet is the business. At $77.57 on 25 August 2026 the shares are fairly valued against the triangulated fair value of $70.78 (-9%) and are trading at the very top of their 52-week range; the recorded range in the configuration was itself stale because the stock has just made a new high, which is disclosed here rather than smoothed away. On 12× forward earnings the price already embeds the model's mid-cycle path, and the twelve-month probability-weighted target of $77.40 sits just beneath the quote. The decisive variable is whether the funding advantage behind that margin survives a full deposit-competition cycle. The most damaging risk is that it does not — that the premium margin proves to be a phase of the rate cycle rather than a structural feature of the franchise.
Narrative drafted 2026-08-16 by claude-opus-5 under supervision; reviewed by Marinus 2026-08-16.
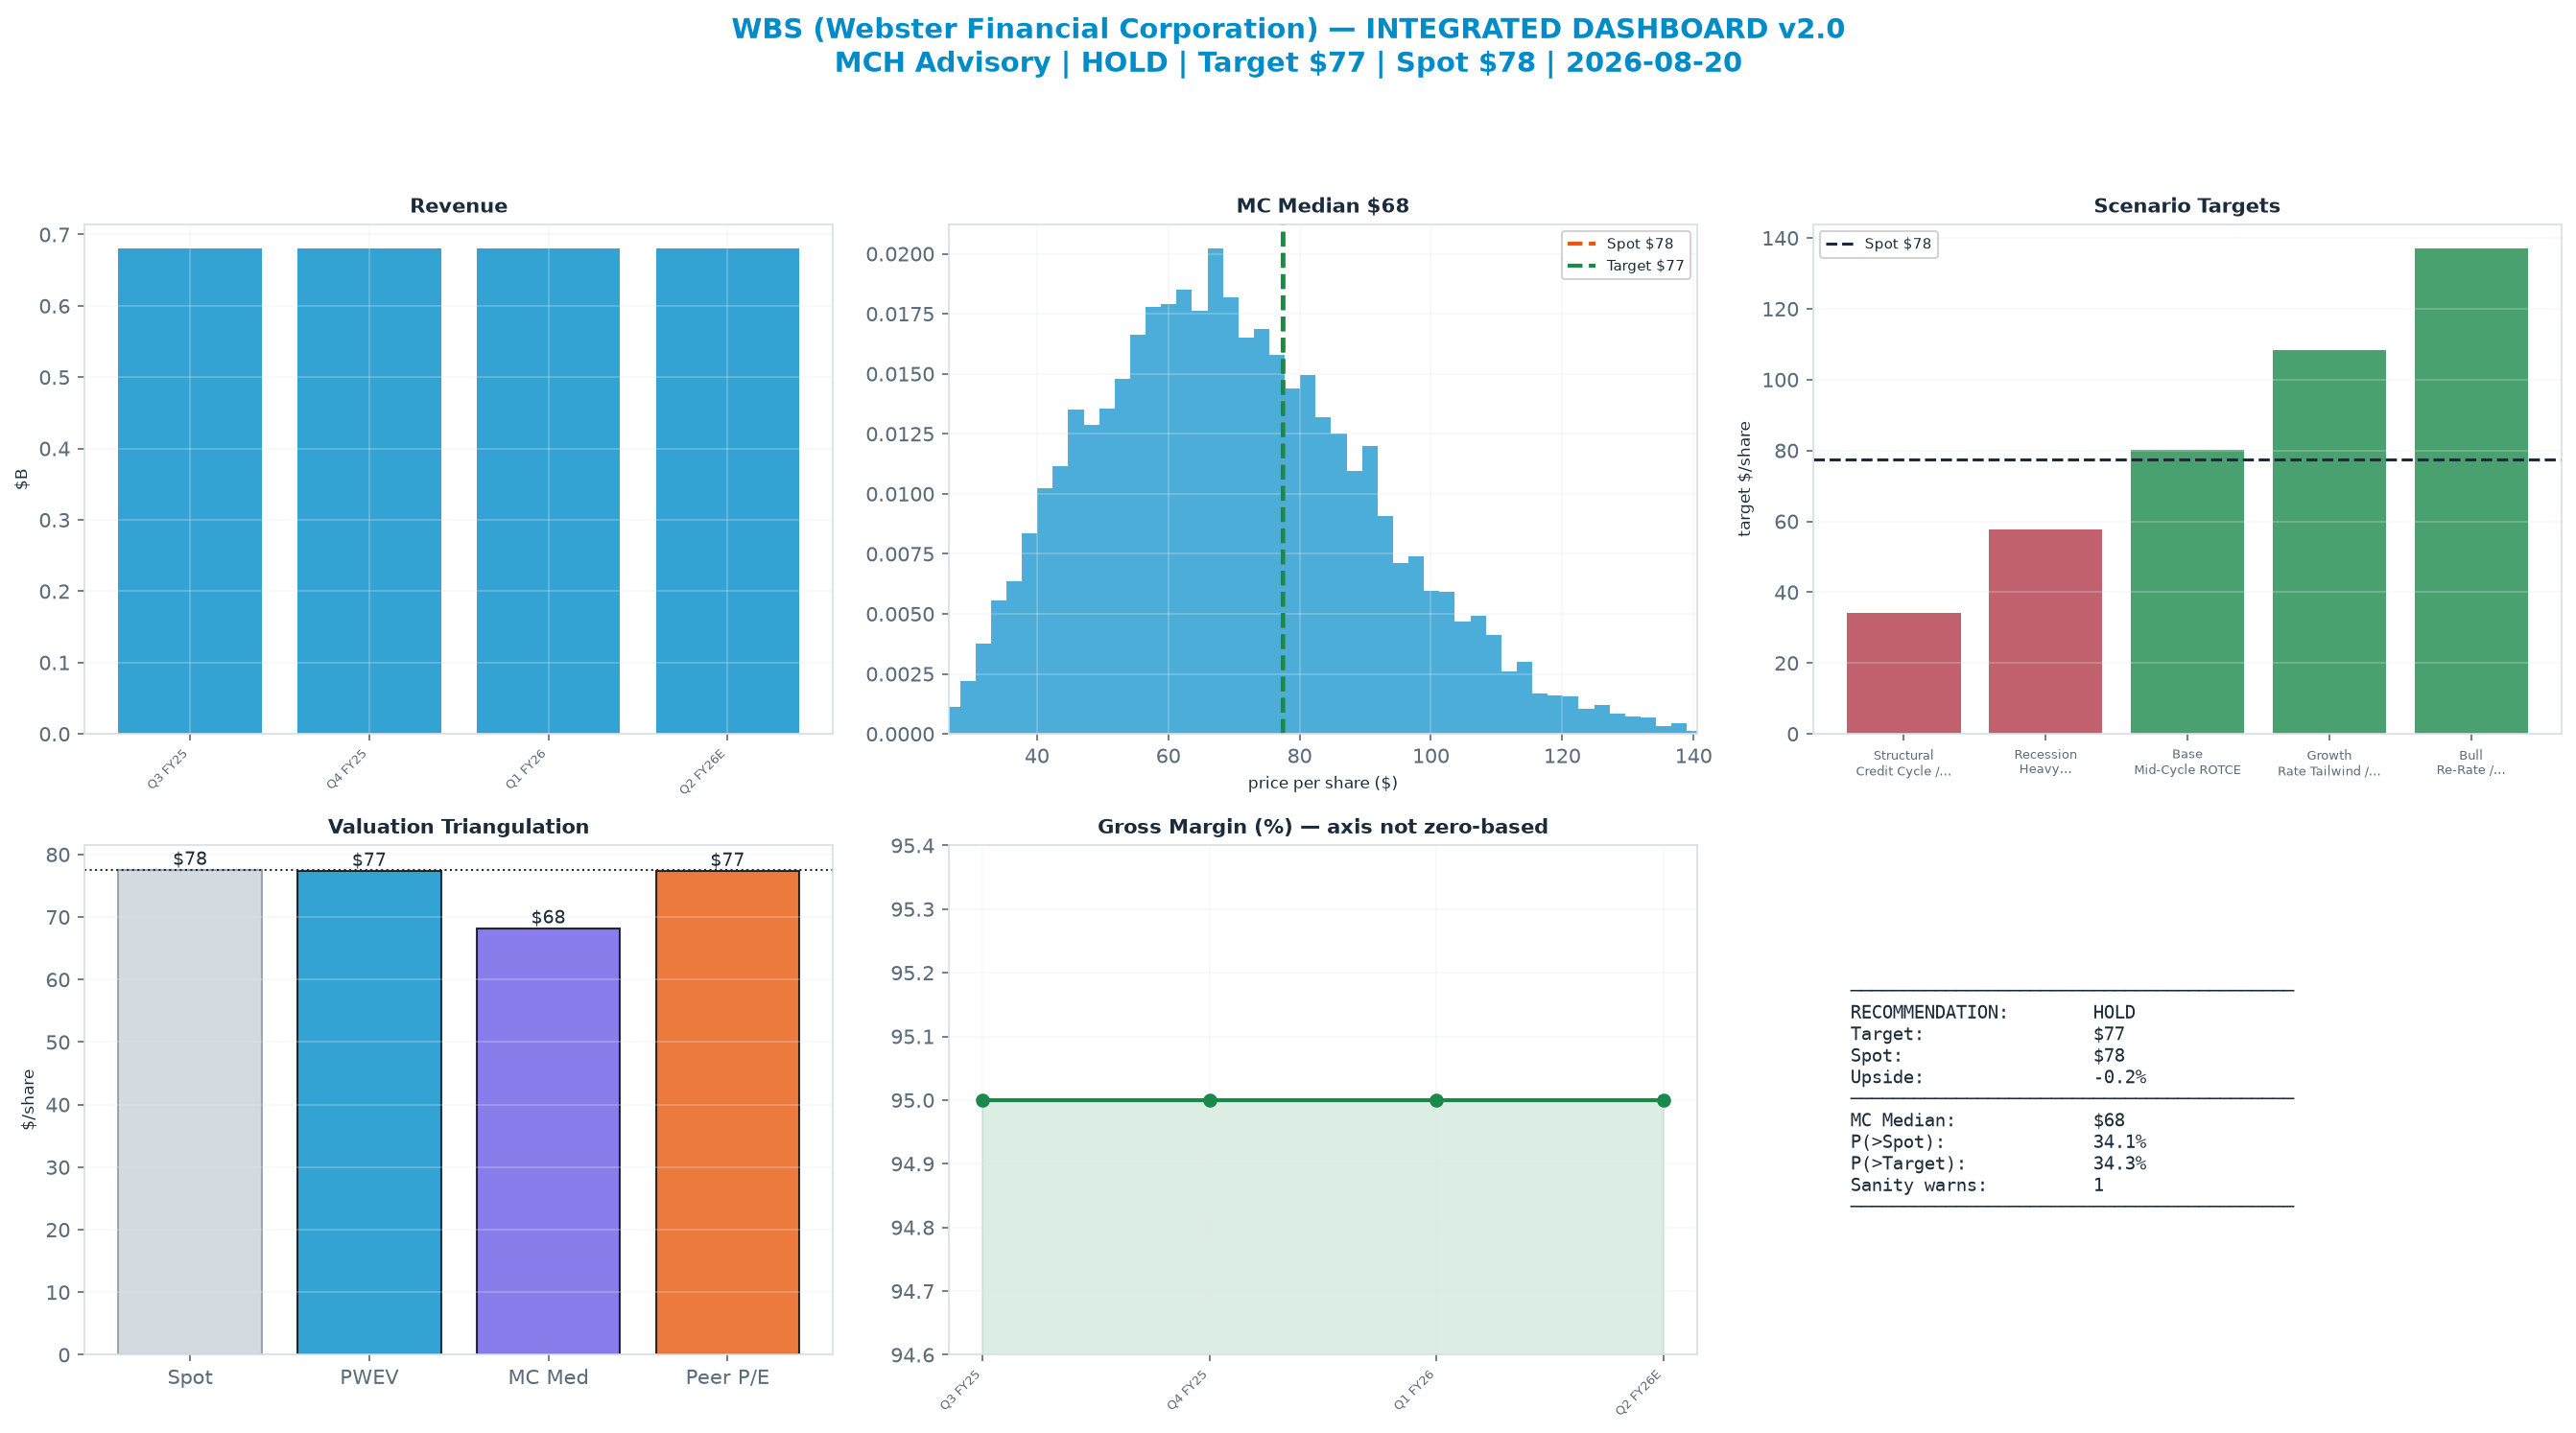
The dashboard below is the whole argument on one page: spot ($77.57) against each valuation anchor, the scenario tree, technicals and the options-implied move.
Anti-Thesis (The Real Bear Case)
A bank that enters a downturn priced at its high has no valuation cushion, and the bear path takes two forms that compound. First, deposit costs reprice faster than assets: the margin the engine carries near 51% narrows, and because pre-provision earnings are a thin spread on a heavily levered balance sheet, a narrowing of that spread flows almost undiluted to the bottom line. Second, credit normalises from an unusually benign level, so provisions rise at the same moment the spread narrows, and the market applies a lower multiple to earnings it now regards as cyclical rather than recurring. Neither leg requires a crisis — only a return to average loss content. Regulation adds a slower drag by raising the capital held against the same book. The model assigns that combination a fifth of the probability and lands its target far below the 52-week low, which is what a real structural case for a levered lender has to look like.
Key Debate
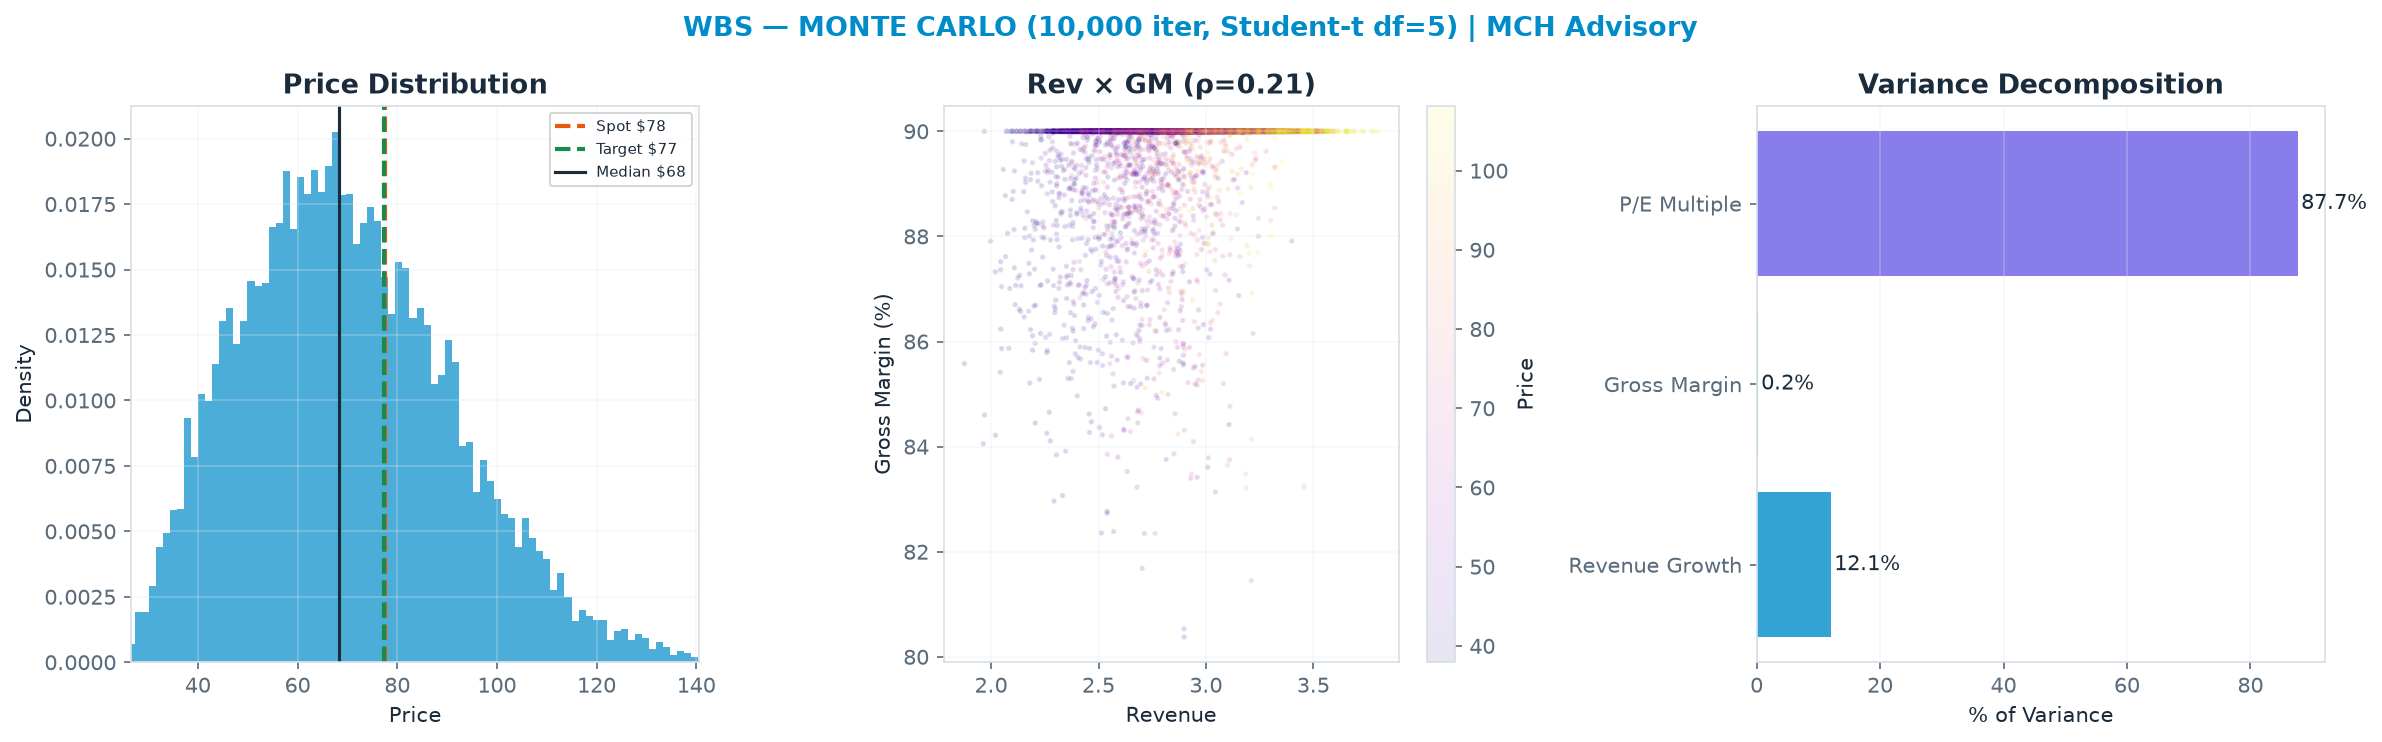
P/E Multiple explains 88% of Monte Carlo outcome variance — i.e. value is set by the multiple the market will pay, a rate/sentiment regime bet as much as an earnings bet.
What the Market Is Pricing In
At the current price, the market pays 12.0× consensus forward EPS, and a peer median 12.0×.
Variant perception: the house view is in-line with consensus, and the thesis is primarily FCF-driven.
| Metric | Consensus | House | Importance |
|---|---|---|---|
| Revenue | 3.0 | 2.9 | High |
| EPS | 6.5 | 6.5 | Medium |
| Target price | 76.2 | 77.4 | Medium |
Scenario Analysis
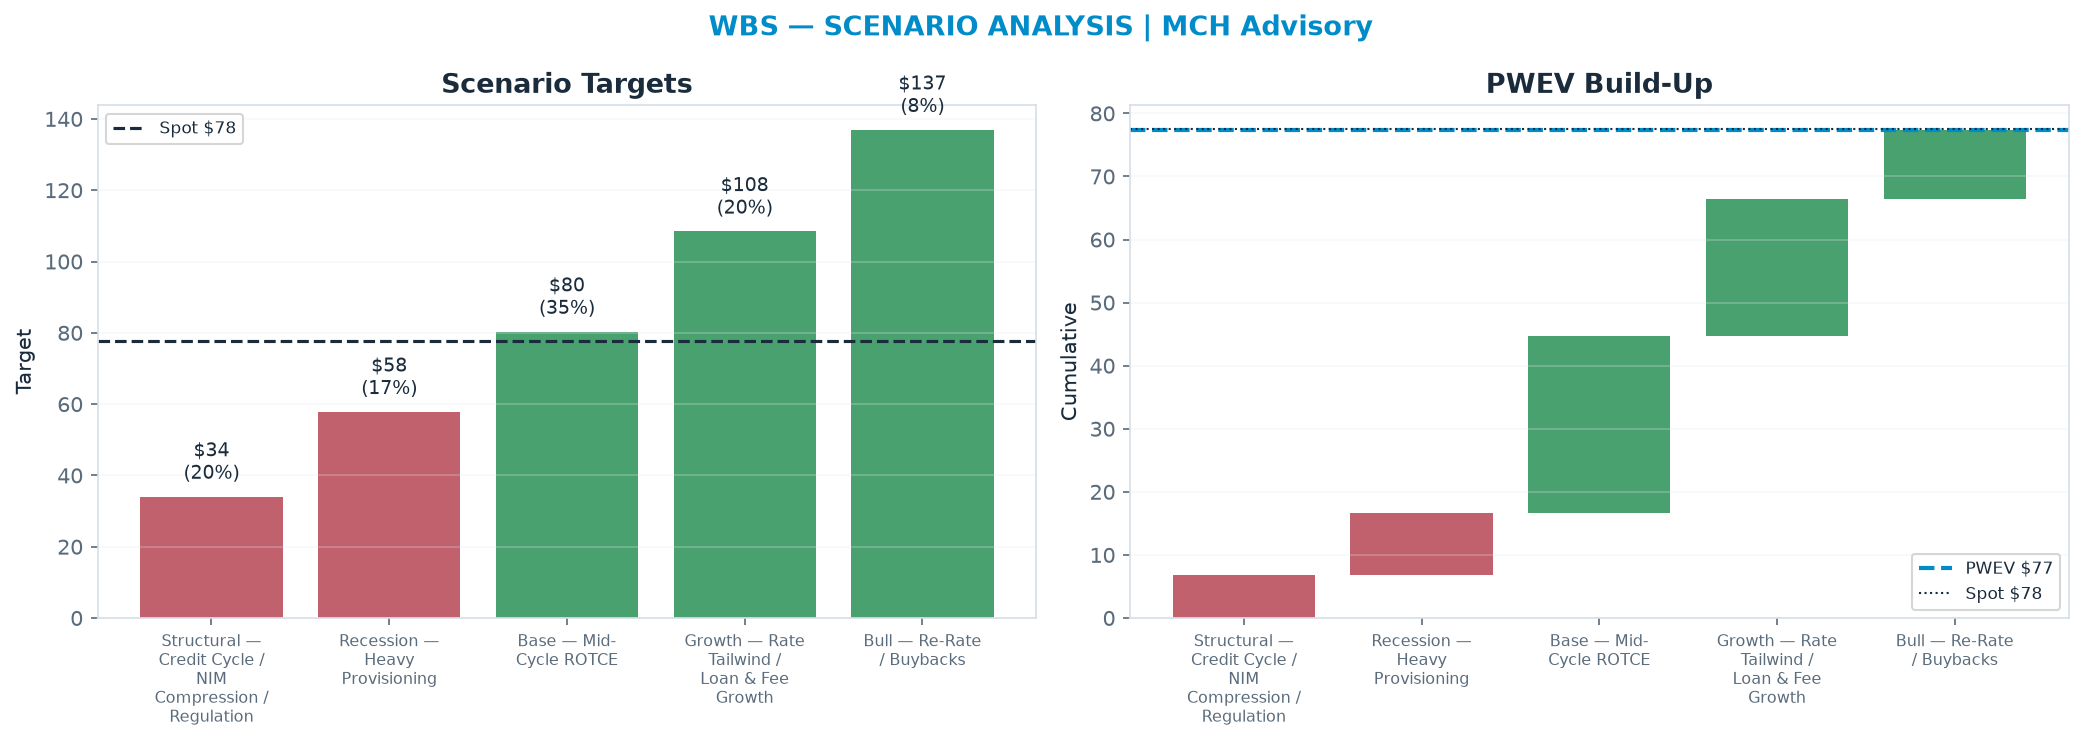
The scenario tree spans a structural 'Structural — Credit Cycle / NIM Compression / Regulation' downside ($34.06) to a 'Bull — Re-Rate / Buybacks' bull case ($137); the probability-weighted blend (PWEV $77.40) is -0% versus spot.
| Scenario | Probability | Target | Return vs spot |
|---|---|---|---|
| Structural — Credit Cycle / NIM Compression / Regulation | 20% | $34.06 | -56% |
| Recession — Heavy Provisioning | 17% | $57.83 | -25% |
| Base — Mid-Cycle ROTCE | 35% | $80.32 | +4% |
| Growth — Rate Tailwind / Loan & Fee Growth | 20% | $108 | +40% |
| Bull — Re-Rate / Buybacks | 8% | $137 | +77% |
| Probability-Weighted (PWEV) | — | $77.40 | -0% |
Share-count charge: none applied. The probability-weighted value above is the gross per-share figure — no annual dilution is deducted — stock-based compensation runs at 2.1% of revenue; free cash flow net of SBC is $0.95B. SBC is therefore disclosed, not charged: read the per-share figures as before dilution.
Scenario rationale — the driver path behind every target:
- Structural — Credit Cycle / NIM Compression / Regulation (20%, $34.06). Structural impairment — credit cycle / NIM compression / regulation: earnings AND the multiple compress together. Target sits below the 52-week low by construction.
- Recession — Heavy Provisioning (17%, $57.83). Cyclical downturn — earning-asset growth + net interest spread + credit costs + fee income weakens for 1–2 years before normalising.
- Base — Mid-Cycle ROTCE (35%, $80.32). Mid-cycle — normalised earning-asset growth + net interest spread + credit costs + fee income; disciplined capital allocation; steady returns.
- Growth — Rate Tailwind / Loan & Fee Growth (20%, $108). Upside — rate tailwind + loan & fee growth lifts earnings above mid-cycle; the multiple expands modestly.
- Bull — Re-Rate / Buybacks (8%, $137). Upside tail — sustained tight conditions or a structural re-rate on rate tailwind + loan & fee growth.
Valuation Triangulation
Four weighted anchors — an intrinsic dcf, a scenario-weighted pwev, a monte carlo median (student-t + regime switching) and a peer p/e re-rate — read them with their basis in mind. The Monte Carlo, the DCF terminal and any peer re-rate key off a market multiple, so they are not fully independent; only discounted cash flows themselves are genuinely multiple-free. The discipline is to read the spread and weight the cash-based view, not to treat four numbers as four independent votes.
| Method | Basis | Fair Value | vs Spot | Weight in this name's blend |
|---|---|---|---|---|
| Monte Carlo median (Student-t + regime) | multiple | $68.21 | -12% | 18% (declared 15%) |
| Peer P/E re-rate | multiple | $77.40 | -0% | 12% (declared 10%) |
| Peer EV/Revenue re-rate | multiple | $79.03 | +2% | 0% — cross-check only |
| Scenario PWEV | multiple | $77.40 | -0% | 29% (declared 25%) |
| Justified P/B (ROE-based) | book value × ROE | $65.27 | -16% | 41% (declared 35%) |
| Triangulated (weighted) | — | $70.78 | -9% | 100% |
The house blend DECLARES five anchor weights — DCF 35%, scenario PWEV 25%, Monte Carlo 15%, sum-of-parts 15%, peer re-rate 10%. For this name sum-of-parts is not computed, so 15% of the declared weight is redistributed across the anchors that exist — which is why the weights above differ from the declared ones. The fair value is unaffected by this disclosure; the blend has always worked this way.
Peer EV/Revenue re-rate — 0% weight: it duplicates the peer-multiple information already carried by the Peer P/E anchor while ignoring margin mix; weighting both would double-count the peer view. Shown as a cross-check.
Book Value, ROE & Capital Returns
For a bank or insurer the cash-flow DCF is the wrong intrinsic anchor — capital is the product. Value is set by return on equity vs cost of equity against book value: the Gordon-justified multiple is P/B = (ROE − g) / (COE − g).
| Metric | Value |
|---|---|
| Book value / share | $57.33 |
| Return on equity (ROE) | 10.9% |
| Cost of equity (assumed) | 10.0% |
| Current P/B | 1.35x |
| Justified P/B (ROE-based) | 1.14x |
| Justified value / share | $65.27 (-16%) |
ROE of 10.9% clears the ~10% cost of equity — which is why a modest justified P/B of 1.14x (vs 1.35x current) is warranted. The justified value sits -16% vs spot; that gap, plus the credit / underwriting cycle in the scenarios, is the debate. The Monte Carlo and scenario PWEV carry the earnings (P/E) view; this block carries the book-value view.
Monte Carlo — the outcome distribution
10,000 paths, Student-t shocks (fat tails) with a regime-switching overlay. The median lands at $68.21 and 34% of paths finish above spot. The variance decomposition shows the p/e multiple is the dominant swing factor (88% of variance). Value is a multiple bet: fundamentals move the answer far less than the rating does.
Peer benchmarking — relative value
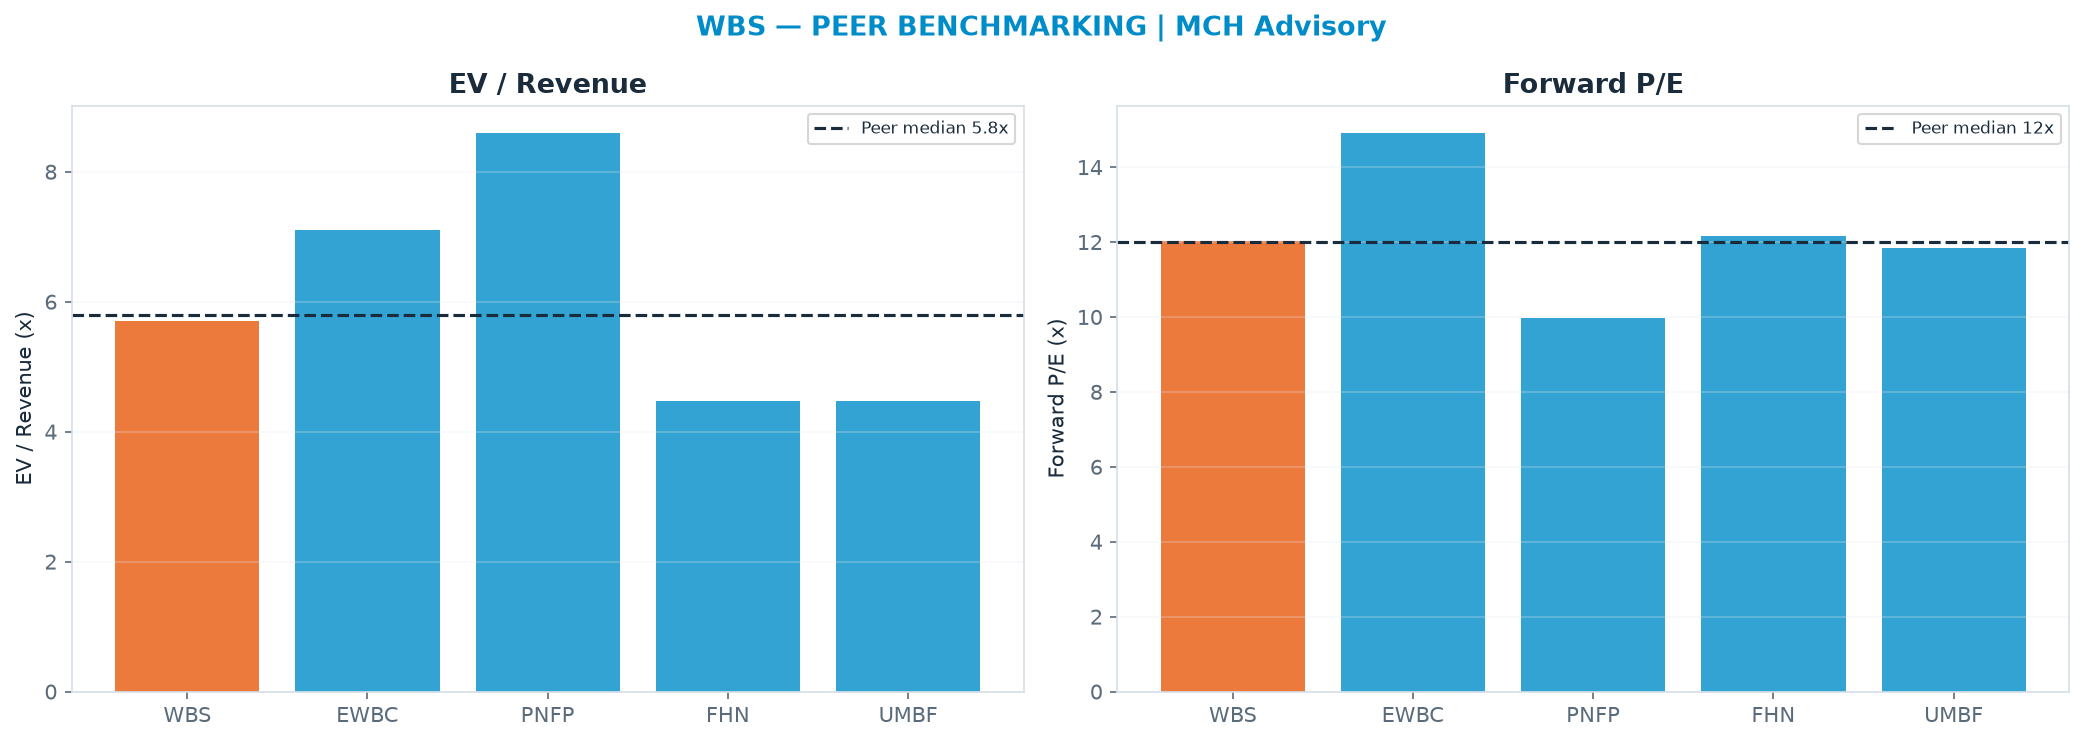
Against the peer cohort, re-rating to the peer-median forward multiple (P/E 12.0x) implies $77.40. A premium is only justified by superior growth/margins; otherwise it is multiple risk. Weighted just 12% so market sentiment does not set the fair value.
Across all anchors the spread is 18% of the median — moderate (healthy method disagreement — read the blend with care).
Peer Quality & Weighting
| Peer | Fwd P/E | Growth | Op margin | Quality | Weight cap |
|---|---|---|---|---|---|
| EWBC | 14.9× | 5% | 65% | direct | 100% |
| PNFP | 10.0× | 5% | 47% | direct | 100% |
| FHN | 12.2× | 5% | 40% | direct | 100% |
| UMBF | 11.8× | 5% | 51% | direct | 100% |
Quality-weighted forward P/E: 12.2× (simple median 12.0×). Direct peers count 100%, segment 50%, broad 25%.
Historical-range cross-check: 52-week range $51.75–$79.07, centre $64.00 (-18% vs spot); spot sits at the 95th percentile of the range. Low-weight mean-reversion cross-check, not a fundamental anchor.
Risk / Reward & Margin of Safety
| Metric | Value |
|---|---|
| Upside to triangulated FV | $70.78 (-9% vs spot · triangulated FV) |
| Downside to bear case (Structural — Credit Cycle / NIM Compression / Regulation) | $34.06 (-56% vs spot · bear scenario) |
| Reward-to-risk ratio | withheld — the triangulated FV is at or below spot, so there is no reward leg to divide by the risk leg |
| Margin of safety (FV vs spot) | -10% |
| P(price > spot) — Monte Carlo | 34% |
That ratio compares triangulated upside against the probability-weighted bear target, not the extreme tail; with a leg missing it is withheld rather than computed from a magnitude. Bull case (Bull — Re-Rate / Buybacks): $137.
Company Overview & Business Model
Webster Financial Corporation — FINANCIAL SERVICES · BANKS - REGIONAL. Webster Financial Corporation is the banking holding company for Webster Bank, a National Association that provides a variety of banking, investment, and financial services to individuals, families, and businesses in the United States. The company is headquartered in Waterbury, Connecticut.
How it makes money.
| Segment | Rev mix | Growth | Op margin | Key driver |
|---|---|---|---|---|
| Banking (NII + Fees) | 100% | +5% | 51% | earning-asset growth + net interest spread + credit costs + fee income |
Edge. Narrow moat — inferred from a 51% operating margin and the banking (NII and fees) business model. Some pricing power / share stability; terminal multiple near the market.
Revenue-Segment Breakdown
The company-specific drivers behind the valuation — each segment carries its own growth, margin, multiple and capex intensity. (Tags: FACT reported · ESTIMATE from disclosures · INFERENCE judgment.)
| Segment | Revenue | Mix | Growth | Op margin | EBIT | Multiple | Capex % | Tag |
|---|---|---|---|---|---|---|---|---|
| Banking (NII + Fees) | $2.7B | 100% | 5% | 51% | $1.4B | 12.0x | 1% | ESTIMATE |
| EBIT = segment revenue × operating margin (segment EBITDA not shown — per-segment D&A is not separately disclosed). |
Named Exposures
Demand & pricing cycle (FACT/ESTIMATE)
| Dimension | Assessment |
|---|---|
| driver | earning-asset growth + net interest spread + credit costs + fee income |
| net_debt_or_cash_b | -2.76 |
Capital intensity & shareholder returns (ESTIMATE)
| Dimension | Assessment |
|---|---|
| capex_pct_revenue | 0.01 |
| div_yield | 0.021 |
Structural risk vs optionality (INFERENCE)
| Dimension | Assessment |
|---|---|
| downside | credit cycle / NIM compression / regulation |
| upside | rate tailwind + loan & fee growth |
Industry Context — Financials — Banks
This name sits in the Financials — Banks cluster as a banking (NII + fees) name. loan growth + net interest margin + credit costs + ROTCE + capital return. Its scenarios are not guessed in isolation — they inherit a single, shared view of the cluster's driver cycle, so the names that depend on the same event are mutually consistent.
Value chain: EWBC (banking (NII + fees)) · NLY (banking (NII + fees)) · PNFP (banking (NII + fees)) · ALLY (banking (NII + fees)) · WBS (banking (NII + fees)) · FHN (banking (NII + fees)) · UMBF (banking (NII + fees)) · WTFC (banking (NII + fees)) · ZION (banking (NII + fees)) · ONB (banking (NII + fees)) · CFR (banking (NII + fees)) · SSB (banking (NII + fees)) · COLB (banking (NII + fees)) · FCFS (banking (NII + fees)) · WAL (banking (NII + fees)) · PB (banking (NII + fees)) · CBSH (banking (NII + fees)) · VLY (banking (NII + fees)) · GBCI (banking (NII + fees)) · FNB (banking (NII + fees)) · UBSI (banking (NII + fees)) · STWD (banking (NII + fees)) · HWC (banking (NII + fees)) · FLG (banking (NII + fees)) · HOMB (banking (NII + fees)) · ASB (banking (NII + fees)) · OZK (banking (NII + fees)) · FFIN (banking (NII + fees)) · SLM (banking (NII + fees)) · IBOC (banking (NII + fees)) · TCBI (banking (NII + fees))
| Shared state | Capex path | House view | This name implies |
|---|---|---|---|
| Credit Cycle / NIM Compression / Regulation | not stated | 37% | 37% |
| Mid-Cycle — ROTCE + Loan Growth | not stated | 35% | 35% |
| Upside — Rate Tailwind / Capital Return | not stated | 28% | 28% |
Mapping note: name-level 'Structural — Credit Cycle / NIM Compression / Regulation' (20%) + 'Recession — Heavy Provisioning' (17%) map to cluster Credit Cycle / NIM Compression / Regulation (37%); name-level 'Growth — Rate Tailwind / Loan & Fee Growth' (20%) + 'Bull — Re-Rate / Buybacks' (8%) map to cluster Upside — Rate Tailwind / Capital Return (28%) — the cluster row is the SUM of the mapped scenario probabilities, not a different estimate.
On the cluster's key downside — Credit Cycle / NIM Compression / Regulation — this name implies 37% vs the cluster house view of 37% (in line with the house). The cluster's full cross-stock reconciliation governs that the names which ride the same capex cycle assign it comparable odds.
Structure: Shared State — The Financials — Banks cycle is the shared macro driver. Driver — loan growth + net interest margin + credit costs + ROTCE + capital return. Dispersion — Members differ by cyclicality (quality compounders vs deep cyclicals).
Balance Sheet & Liquidity
| Metric | Value |
|---|---|
| Net debt | $1.9B — n/a |
| Interest coverage (EBIT / interest) | 0.8x |
| Current ratio | 0.03x |
| Cash & ST investments | $2.5B |
Balance-sheet data as of 2025-12-31 (Alpha Vantage).
Capital Allocation
| Metric | Value |
|---|---|
| Free cash flow | $1.0B |
| Buybacks / dividends | $0.6B / $0.3B |
| Total shareholder yield | 7.1% |
| Payout as % of FCF | 89.1% |
| Reinvestment (capex / OCF) | 4.7% |
| SBC as % of FCF | 5.6% |
| Allocation stance | returns-heavy |
Free-Cash-Flow Quality
| Metric | Value |
|---|---|
| FCF margin | 37.4% |
| FCF conversion (FCF / net income) | 100.6% |
| FCF yield | 8.0% |
| Capex intensity (capex / revenue) | 1.9% |
| FCF − SBC (diagnostic) | $0.9B |
Accounting quality: SBC 1% of revenue; cash conversion (OCF/NI) 106% — cash-backed.
Earnings-Call Disconfirmation & Sentiment
Derived signals from the MCH market-data store (Alpha Vantage transcripts + news). Quantitative tone only — a disconfirmation flag, not a substitute for reading the call.
Management vs analyst tone (2025Q4): management +0.34 vs analyst floor +0.06 → delta +0.27 (n=40 mgmt / 34 Q&A; 23rd pctile across the S&P book, z -0.9).
Flag: TYPICAL — management-vs-analyst tone within the normal cross-sectional range.
| Quarter | Mgmt | Analyst | Delta |
|---|---|---|---|
| 2025Q4 | +0.34 | +0.06 | +0.27 |
| 2025Q3 | +0.36 | +0.12 | +0.25 |
| 2025Q2 | +0.59 | +0.50 | +0.09 |
| 2025Q1 | +0.25 | +0.06 | +0.19 |
News (last 365d, 17 articles): avg ticker sentiment +0.17 (bullish 24% / bearish 0%)
Consensus & Market Expectations
| Reference | Value |
|---|---|
| Street target (mean) | $76.18 (-2% vs spot · street) |
| House target | $77.40 (+1.6% vs street) |
| Sell-side coverage | 14 analysts (SB 1 / B 1 / H 11 / S 1 / SS 0; net score 0.07) |
| Consensus FY EPS | $6.46; house in-line (-0.2%) |
| Consensus FY revenue | $3.0B; house below (-3.5%) |
_Consensus figures: Alpha Vantage sell-side aggregates. Where the house view sits materially above or below the street, the divergence is itself a datum — see the thesis.
Catalyst Calendar
- 2026-10-22 (~63d) — Quarterly earnings — est. EPS $1.62 (AV EARNINGS_CALENDAR)
Forecast Track Record
- EPS surprise: beat 62% of the last 8 quarters; average surprise +1.8%.
Catalyst Timeline
5 catalysts in the next 90 days (of 13 tracked). Importance 1–3; confidence 0–1.
| When | Catalyst | Type | Importance | Confidence |
|---|---|---|---|---|
| 2026-09-16 (in 22d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2026-09-18 (in 24d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
| 2026-10-14 (in 50d) | September CPI | macro | ●● | 0.8 |
| 2026-10-22 (in 58d) | Quarterly earnings | earnings | ●●● | 0.95 |
| 2026-10-28 (in 64d) | FOMC rate decision + press conference | macro | ●● | 0.8 |
| 2026-12-09 (in 106d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2026-12-18 (in 115d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
| 2027-01-27 (in 155d) | FOMC rate decision + press conference | macro | ●● | 0.8 |
| 2027-03-17 (in 204d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2027-03-19 (in 206d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
| 2027-04-28 (in 246d) | FOMC rate decision + press conference | macro | ●● | 0.8 |
| 2027-06-09 (in 288d) | FOMC rate decision + SEP dot plot | macro | ●● | 0.8 |
| 2027-06-18 (in 297d) | Quarterly options-expiry cluster (3rd Friday) | opex_cluster | ● | 1.0 |
_Sources: extended.catalysts, data/catalysts/
Scenario Macro & Key Risks
| Scenario | Macro assumption | Key risk |
|---|---|---|
| Structural — Credit Cycle / NIM Compression / Regulation | Cluster state Credit Cycle / NIM Compression / Regulation — see the Industry Context table for the house probability | Path-dependency: a single disappointing print can shift the book toward the adjacent-bear state. |
| Recession — Heavy Provisioning | Cluster state Credit Cycle / NIM Compression / Regulation — see the Industry Context table for the house probability | Path-dependency: a single disappointing print can shift the book toward the adjacent-bear state. |
| Base — Mid-Cycle ROTCE | Cluster state Mid-Cycle — ROTCE + Loan Growth — see the Industry Context table for the house probability | Path-dependency: a single disappointing print can shift the book toward the adjacent-bear state. |
| Growth — Rate Tailwind / Loan & Fee Growth | Cluster state Mid-Cycle — ROTCE + Loan Growth — see the Industry Context table for the house probability | Path-dependency: a single disappointing print can shift the book toward the adjacent-bear state. |
| Bull — Re-Rate / Buybacks | Cluster state Upside — Rate Tailwind / Capital Return — see the Industry Context table for the house probability | Path-dependency: a single disappointing print can shift the book toward the adjacent-bear state. |
Decision Rules (Machine-Checked)
Stance: Hold — 0 bullish / 0 bearish / 0 caution rules triggered of 6 evaluable (0 lacked data).
| Rule | Condition | Observed | Triggered |
|---|---|---|---|
| R1-valuation-stretch | expected return vs fair value < -12 (upside_pct) |
-0.22 | no |
| R2-valuation-opportunity | expected return vs fair value > 15 (upside_pct) |
-0.22 | no |
| R3-street-revisions | street net rating stance < -0.25 (extended.consensus.street_score) |
0.07 | no |
| R4-earnings-quality | cash conversion of earnings < 80 (extended.accounting_quality.cash_conversion_pct) |
105.5 | no |
| R5-technical-breakdown | price vs 200-day SMA < 0.85 (technicals.sma_200) |
1.12 | no |
| R6-vol-regime-shift | IV/RV vol-risk premium > 1.4 (options_overlay.iv_rv) |
1.01 | no |
Machine-checked rules over disclosed inputs. The authored falsification triggers elsewhere in this report are analyst judgment and are NOT evaluated here. The stance is what the model's own rules read on this name; it does not modify the published research rating, and it is not advice to any reader.
Reasons the Thesis Could Fail (Falsifiable)
Pre-registered signals that would break the thesis — each polices a specific scenario boundary and is checked at every earnings update:
- Organic revenue growth / order backlog < flat-to-negative for two consecutive quarters (2 consecutive prints). Sustained demand rollover breaks the base case toward the recession scenario.
- FY revenue ($B) < 2.8 (next reported fiscal year). (rationale withheld pending re-authoring — frozen figure or verdict)
- Probability-weighted fair value (PWEV) at the next re-run < 77.57 (any scheduled re-run). (rationale withheld pending re-authoring — frozen figure or verdict)
Fact / Inference / Speculation
- FACT: Spot $77.57; 52-week range $51.75–$79.07; engine rating HOLD; house target $77.40 (-0%). (source: Alpha Vantage 2026-08-20, 25 August 2026)
- INFERENCE: Triangulated FV $70.78 (-9% vs spot · triangulated FV); the rating tracks the Monte-Carlo + scenario-PWEV core; the cash-flow anchor sits below the multiple-discipline core.
- SPECULATION: At current prices the embedded bet is that the market keeps paying the current multiple through the capex cycle — a regime call the engine cannot verify from fundamentals alone.
Conviction Score
Research Conviction measures the strength and quality of the research setup — input coverage, financial quality, valuation support, process agreement. It is NOT the probability that the recommendation succeeds; the forecast track record section is the evidence on that.
70.2/100 (confidence band 58.2–82.2), 92nd percentile of 858 covered names (as of 2026-08-24). Weighted composite under config ros-1.19.0 — every component and its inputs below.
| Component | Score (0–100) | Weight | Inputs |
|---|---|---|---|
| business quality | 85 | 15% | extended.fcf_quality.fcf_margin_pct, extended.balance_sheet.net_debt_to_ebitda, extended.accounting_quality.cash_conversion_pct |
| financial strength | — | 10% | extended.balance_sheet.net_debt_to_ebitda, extended.balance_sheet.interest_coverage |
| valuation | 50 | 15% | upside_pct |
| growth | 58 | 10% | reconciliation.ttm_revenue_billions, reconciliation.fy_guide_revenue_billions |
| earnings visibility | 62 | 10% | extended.forecast_accuracy.eps_surprise.beat_rate_pct |
| moat | 65 | 10% | enrichment.moat.rating |
| technical trend (heuristic — no validation record; weight change reserved for AM-060) | 83 | 10% | technicals.rsi, technicals.sma_50, technicals.sma_200 |
| macro tailwinds | 100 | 10% | industry_context.house |
| risk profile | 60 | 10% | monte_carlo.prob_above_current, monte_carlo.p10, monte_carlo.p90, monte_carlo.median |
Missing inputs (financial strength) are excluded and the remaining weights renormalised; the confidence band widens accordingly.
Score history: 70.3 → 70.3 → 70.4 → 70.4 → 70.4 → 70.1 → 70.2 → 70.2.
Probability-Weighted Return Profile
Horizon: 1 year — at this horizon CAGR equals total return by definition. Expected values are the probability-weighted sums over the full scenario set below.
| Scenario | Probability | Target | Total return | Contribution |
|---|---|---|---|---|
| Structural — Credit Cycle / NIM Compression / Regulation | 20% | $34.06 | -56.1% | -11.2pp |
| Recession — Heavy Provisioning | 17% | $57.83 | -25.4% | -4.3pp |
| Base — Mid-Cycle ROTCE | 35% | $80.32 | +3.5% | +1.2pp |
| Growth — Rate Tailwind / Loan & Fee Growth | 20% | $108 | +39.8% | +8.0pp |
| Bull — Re-Rate / Buybacks | 8% | $137 | +76.6% | +6.1pp |
| Aggregate | Value |
|---|---|
| Expected return (gross, 1y) | -0.2% |
| Expected return net of SBC dilution | -0.2% |
| Outcome dispersion (σ, from MC p10–p90) | 28.0% |
| Expected Sharpe (rf 4%) | -0.15 |
| Downside expectation (prob-weighted loss branches) | -15.5% |
The gross expected return is the probability-weighted scenario return (it reconciles to the gross PWEV); the diluted figure applies the SBC share-count charge and matches the published PWEV-based target.
Expected Alpha
Expected return minus the return this name is REQUIRED to deliver for its risk (1-year horizon). Constants are pre-registered (preregistered-static (amendment #2, 2026-07-29); not fitted to MCH outcomes).
| Component | Value |
|---|---|
| Expected return (gross, 1y) | -0.2% |
| Risk-free rate | 4.01% (1y proxy (3m/2y midpoint; AV lacks a 1y tenor), as of 2026-08-13) |
| Beta (shrunk, 1y vs SPY) | 0.88 (as of 2026-08-20) |
| Equity risk premium | 4.5% |
| Required return | 8.0% |
| Expected alpha | -8.2% |
| Alpha per unit risk (EA/σ) | -0.29 |
A negative expected alpha does not change the rating — it says the expected return does not clear the risk-adjusted hurdle at today's price. Rating mechanics are unchanged by this section.
Probability Cross-Checks
Not authoritative. The scenario probabilities in this report are AUTHORED — a judgement about how the world might go, not a measurement. Nothing below modifies them, the target, the rating or any position size. These checks ask only whether anything outside our own model agrees with us; where it does not, that is information for the reader, not a correction we have quietly applied.
| Cross-check | Ours | Comparator | Reading |
|---|---|---|---|
| Scenario spread vs options market | 39.1% (1σ) | 13.3% implied | our scenarios are far wider than the options market prices |
| Mass above spot: scenarios vs our own MC | 63.0% | 34.1% | the scenario weights and the MC parameters disagree about our OWN view — this is a model-coherence issue, not a market disagreement |
| Realised scenario frequency | 23 dated anchors | — | 23 dated anchors available; realised-vs-prior comparison is now meaningful. |
Authored set: 5 scenarios, probabilities summing to 1.0, mean target $77.4.
Flagged for review: scenario spread vs the options market, internal coherence (authored mass vs Monte Carlo). A flag marks a disagreement worth understanding — it does not imply either side is wrong.
Factor Exposures
Cross-sectional percentiles over 858 covered names (style scores sector-demeaned; thematic = return-beta to the theme's proxy ETF). 50 = estate median.
| Style | Percentile | Theme | Percentile | |
|---|---|---|---|---|
| Growth | 81 | AI | 61 | |
| Value | 54 | Cloud | 45 | |
| Quality | 68 | Semis | 66 | |
| Momentum | 80 | Consumer | 58 | |
| Low-Vol | 96 | Rates | 37 | |
| USD | 57 | |||
| Energy | 80 |
Market interaction: correlation vs SPY +0.56, vs QQQ +0.45 (trailing ~1y daily returns).
Sections withheld from publication under the MCH Analysis operating model (2026-09-30): contract-specific option structures and position sizing are not published. The rest of this report is preserved as published.
Rating Bridge
Rating = HOLD because:
- Probability-weighted scenario value implies -0% vs spot
- Monte Carlo median implies -12% vs spot
- DCF fair value implies -16% vs spot
- Bear case (Structural — Credit Cycle / NIM Compression / Regulation) downside is -56% vs spot
- Net: the valuation anchor itself sits 8.8% below spot, so there is no reward leg to weigh against the bear case and the reward-to-risk ratio is withheld rather than computed off a negative upside. The rating is not asymmetric enough for a Buy and not impaired enough for a Sell — hence Hold.
Assumption Register
| Assumption | Value | Used in | Source |
|---|---|---|---|
| SBC dilution | 0.0%/yr | PWEV, MC, DCF (charged once) | estimate (from SBC/rev) |
| EPS basis | consensus forward EPS (broker-adjusted, non-GAAP) | all forward P/E & scenario multiples | definition |
Inputs, Sources & Confidence
Every load-bearing input, labelled by type and confidence. (reported fact · company guidance · consensus estimate · market data · house estimate · inference.)
| Input | Value | Type | Source | Confidence | Used in |
|---|---|---|---|---|---|
| Revenue TTM | $2.7B | reported fact | 10-K/10-Q via AV | High | Forecast base, EV/Rev |
| FY+1 guided revenue | $2.9B | company guidance | Company guidance | Medium | Forecast, SoP |
| Consensus FY EPS | $6.4622 | consensus estimate | Sell-side consensus via AV | Medium | Variant perception |
| Diluted shares | 0.163B | reported fact | 10-K via AV | High | Market cap, per-share |
| Net debt / cash | $1.855B | reported fact | Balance sheet via AV | High | EV, DCF equity bridge |
Research Provenance
| Field | Value |
|---|---|
| Quantitative engine | mch_stock_engine v2.0 |
| Research OS config | ros-1.19.0 |
| Analysis as-of | 2026-08-25 (prices 2026-08-20) |
| Narrative authorship | claude-opus-5 · Claude Code, supervised, drafted 2026-08-16 |
| Human review | Marinus 2026-08-16 |
| Evidence | 7/8 load-bearing inputs sourced; 11/14 mandated claims cited |
| QA | scanned post-emit by the document-QA layer; the publication label (Draft / Research / Decision-level) is stamped on the published page, not authored here |
Load-Bearing Assumptions
DCF inputs (WACC, terminal multiple) are not applicable to this name's valuation adapter; triangulation leans 41% on DCF, 29% on PWEV, 18% on the Monte Carlo median, 12% on peer-implied value.
Appendix & audit trail — source log, data provenance, disclosures
Source Log
| Source | Type | Date | Used for | Reference |
|---|---|---|---|---|
| Alpha Vantage — GLOBAL_QUOTE / OVERVIEW | market data | 2026-08-20 | Price, market cap, EV, forward P/E | Alpha Vantage 2026-08-20 |
| MCH engine — trailing 252 adjusted closes | derived | 2026-08-20 | 52-week range (vendor's recorded range was stale and was replaced) | trailing 252 sessions of own close history; config value was stale |
| Company income statement (10-K / 10-Q) via Alpha Vantage | reported fact | 2026-08-20 | Revenue, gross/operating margin, EBIT, interest expense | INCOME_STATEMENT / latest annual |
| Company balance sheet (10-K / 10-Q) via Alpha Vantage | reported fact | 2026-08-20 | Cash, debt, net debt, leases, equity, coverage | BALANCE_SHEET / latest annual |
| Company cash-flow statement (10-K / 10-Q) via Alpha Vantage | reported fact | 2026-08-20 | Operating cash flow, capex, FCF, buybacks, dividends, SBC | CASH_FLOW / latest annual |
| Company earnings releases via Alpha Vantage | reported fact | 2026-08-20 | Reported EPS, surprise history | EARNINGS / quarterly |
| Sell-side consensus via Alpha Vantage | consensus estimate | 2026-08-20 | Forward revenue/EPS consensus, analyst count | EARNINGS_ESTIMATES |
| Earnings calendar via Alpha Vantage | market data | 2026-08-20 | Next earnings date, catalyst timing | EARNINGS_CALENDAR |
| Company guidance | company guidance | 2026-08-20 | FY guided revenue / non-GAAP EPS basis | company guidance / earnings call |
| MCH segment model (from filings & disclosures) | house estimate | 2026-08-20 | Segment revenue, margins, multiples, AI decomposition | company_context (authored, tagged) |
| MCH qualitative analysis | inference | 2026-08-20 | Moat, regulatory risk, scenario macro, catalysts | company_context enrichment (authored) |
| MCH investment thesis & falsification triggers | house estimate | 2026-08-20 | Thesis, anti-thesis, thesis-break signals | authored §5.3 |
Citation coverage: 11/14 mandated claims sourced. Filing URLs are not available via the market-data provider; company statements are cited as 10-K/10-Q via Alpha Vantage.
Data Sources
- Prices, fundamentals, options chain, earnings — Alpha Vantage.
- Company filings (10-K / 10-Q) — SEC filings via EDGAR.
Disclosures & Limitations
This report is for informational and research purposes only. It is not personalised investment advice and does not consider any investor's objectives, financial situation, risk tolerance, tax position, or liquidity needs.
- This report is produced by the MCH Advisory quantitative research engine — valuation, scenarios, Monte Carlo and the decision layer are generated systematically from the disclosed inputs and the archetype/industry driver sets, and reviewed rather than written name-by-name. Every figure reconciles to the appendix and every score exposes its inputs.
- No suitability assessment has been performed for any individual.
- Market data may be delayed or inaccurate; figures are as of the analysis date.
- Model outputs (fair values, targets, scenario probabilities) are estimates and may be wrong.
- Forecasts are uncertain; past performance is not indicative of future returns.
- The author or publisher may hold positions in securities mentioned.
- Users should verify information against primary sources (company filings) before acting.
- Investing involves risk of loss; there is no guarantee any target price is achieved.
- Ratings follow a defined research methodology (12-month expected-return thresholds), not individual circumstances.